Barings -

CLOs: More Ways to Find Value

Abstract financial market data with blue lines and colorful blurred lights.

Melissa Ricco
Head of Structured Credit

Meredith Lynch, CFA
Managing Director, High Yield


CLOs continue to offer attractive floating-rate income and meaningful structural protections, supported by resilient loan fundamentals and strong investor demand. But beneath that backdrop, opportunities are shifting across borrowers, markets and the capital structure.

Strong demand and limited new loan supply continue to support CLO valuations, while the floating-rate nature of the asset class has contributed to performance in a higher-rate environment. Although spreads widened modestly toward the end of the third quarter, the move followed an extended period of stability and tightening, bringing potentially more attractive entry points into view.

Across the market, CLOs continue to offer attractive carry and diversification. Senior tranches remain particularly compelling, while periods of volatility are creating select opportunities further down the capital structure.

Fundamentals Remain Healthy

Leveraged loan fundamentals remain healthy overall:

  • Most borrowers continue to generate positive revenue and EBITDA growth, and leverage has improved year over year.
  • Broad deterioration has so far remained contained, with defaults still concentrated among a relatively small group of weaker borrowers.

However, signs of deceleration are emerging. Rising input costs may start to pressure margins, while elevated interest expense could constrain free cash flow for weaker borrowers.

Maturities are also drawing a clearer line between stronger and weaker credits. Many borrowers have successfully extended their maturity profiles, but companies with weaker cash flows, higher leverage or less robust business models may face a higher hurdle as the market turns its attention to 2028 and 2029. The result is greater price dispersion, even among companies in the same sector.

AI is Widening the Lens on Disruption Risk

Software remains a closely watched area of the loan market. Following significant volatility earlier in the year, performance improved during the third quarter as investors began distinguishing more clearly between companies that may benefit from AI and those that may face greater disruption risk.

It’s still too early to establish definitive winners and losers, given the difficulty of quantifying potential effects on revenue, margins and competitive positioning. Software therefore remains investable, but the range of possible outcomes calls for company-specific analysis rather than broad conclusions about the sector.

Beyond software, certain business services and health care technology companies have experienced AI-related volatility.

For CLO investors, the key question is not necessarily how much technology exposure a portfolio contains, but whether managers have a credible framework for:

  • Identifying disruption risk
  • Distinguishing between durable and potentially vulnerable credits
  • Adjusting the portfolio as the effects of AI become clearer

Another area to watch is AI infrastructure financing. Data center and related issuance has so far been concentrated primarily in the investment grade and high yield bond markets, but the broadly syndicated loan market could play a larger role as financing needs expand. This could ultimately introduce loans with different cash flow profiles, construction risks and collateral considerations into CLO portfolios.

The Technical Backdrop is Still Strong

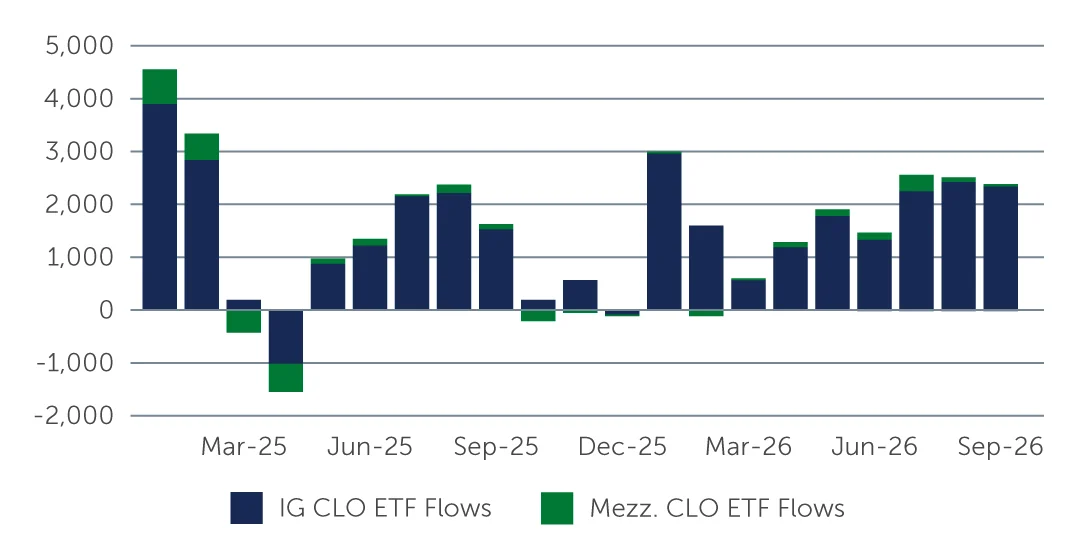
Technical conditions remain strong in both the U.S. and Europe. Demand is broad-based and remains supported by attractive carry and low duration relative to comparably rated fixed income products. CLO ETFs are a growing source of that demand, with the market now exceeding $60 billion in the U.S. and approximately $2 billion in Europe.1

Primary CLO activity remains robust, although much of the recent volume has consisted of refinancings, repricings and resets. Recent spread widening has also improved relative value in the secondary market, giving investors greater flexibility to compare opportunities across primary and secondary markets, as well as across managers, vintages and regions.

Figure 1: Demand Remains Strong, Including from CLO ETF ($ millions)  

Barings chart showing demand from CLO ETFs

Source: BofA Global Research. As of September 30, 2026.

Senior CLOs Look Compelling

Senior CLO tranches continue to offer an attractive combination of carry and downside protection. AAA and AA tranches benefit from meaningful credit enhancement and remain relatively insulated from idiosyncratic weakness in underlying loan portfolios. That combination is particularly valuable amid continued economic, policy and geopolitical uncertainty.

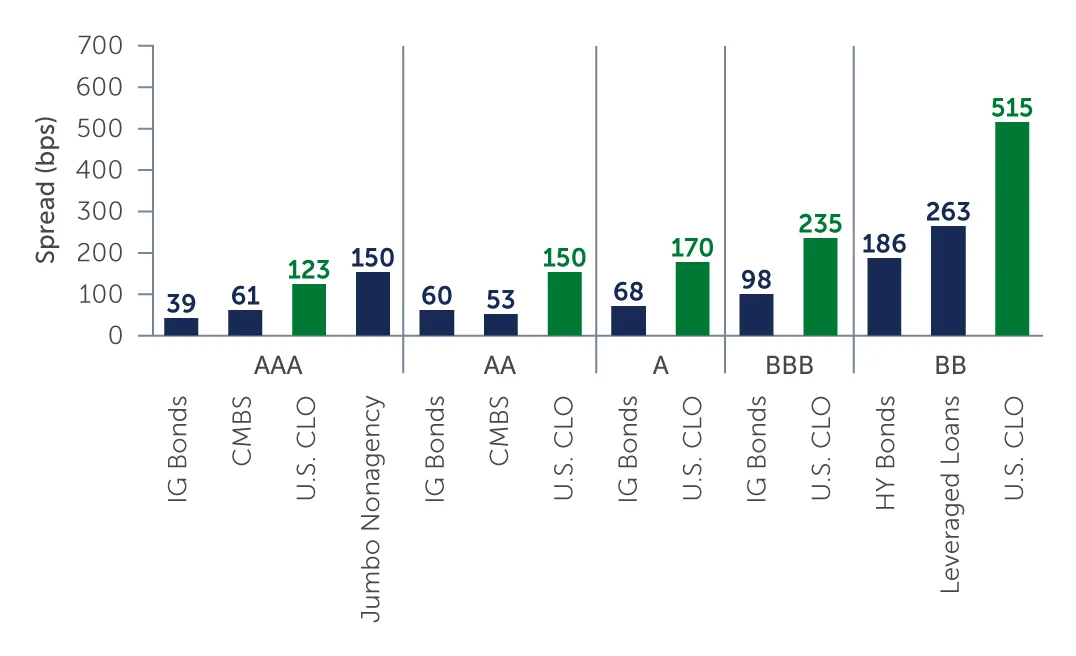
Further down the capital structure, mezzanine spreads could widen if higher rates place additional pressure on riskier portfolios, potentially creating opportunities but also increasing the importance of careful collateral analysis. More broadly, CLOs continue to offer a notable spread pickup relative to similarly rated corporate bonds and CMBS (Figure 2).

Figure 2: CLOs Can Offer a Notable Spread Advantage in Today’s Market

Barings chart comparing CLO spreads with similarly rated corporate bonds and CMBS

Sources: J.P. Morgan US CLO Spreads; BofA Global Research Jumbo Nonagency Spreads; Bloomberg US Aggregate Index –CMBS & Corporate IG; Bloomberg US Corporate High Yield Index; S&P UBS Leveraged Loan Index as of September 30, 2026. Note: Represents New Issue CLO Spreads.

Relative value can also vary considerably across deals. Manager quality, portfolio composition, vintage and structural protections can all influence the risk and compensation offered, even among similarly rated tranches. Looking beyond the headline rating therefore remains essential when comparing opportunities.

A New Consideration for Insurance Investors

Updated NAIC risk-based capital factors are expected to improve the capital treatment of higher-rated CLO tranches held by U.S. life insurers, while increasing charges for tranches rated BBB+ and below. These changes are already contributing to structural innovations in the new-issue CLO market, most notably the emergence of junior single-A tranches, which can offer additional spread over more senior single-A tranches without requiring insurers to step down into BBB risk.

Pricing will ultimately determine whether these tranches offer compelling value. But the change gives insurance investors another reason to compare the structural position, subordination and compensation within the same broad rating category.

An Expanding Market

The opportunity set extends beyond CLOs backed by traditional broadly syndicated corporate loans. Private credit CLOs continue to gain traction, infrastructure CLOs are developing from a small base, and hybrid structures combining private credit and broadly syndicated loans are generating increased interest, particularly in Europe. Commercial real estate CLOs represent another established, if more specialized, application of the structure.

Each segment offers a different underlying exposure, but the common thread is a familiar structure that can provide investors with tranched access to actively managed pools of credit.

The Bottom Line

The CLO market is becoming broader and more differentiated at the same time—giving investors more ways to find value, but also more distinctions to make across borrowers, managers, structures and individual tranches.


READ MORE FROM BARINGS


1. Sources: J.P. Morgan. As of September 21, 2026 (U.S.); BofA. As of September 30, 2026 (Europe).

26-6025286

Forecasts in this document reflect Barings’ market views as of the preparation date and may change without notice. Projections are not guarantees of future performance. Investments involve risk, including potential loss of principal. The value of investments and any income may fluctuate and are not guaranteed by Barings or any other party. PAST PERFORMANCE IS NOT INDICATIVE OF FUTURE RESULTS. Examples, portfolio compositions, and investment results shown are for illustrative purposes only and do not predict future outcomes. Actual investments may differ significantly in size, composition, and risk. No assurance is given that any investment will be profitable or avoid losses. Currency exchange rate fluctuations may impact investment value. Prospective investors should consult the offering documents for detailed information and specific risk factors related to any Fund/Strategy mentioned.

Read less

Barings is the brand name for the worldwide asset management and associated businesses of Barings LLC and its global affiliates. Barings Securities LLC, Barings (U.K.) Limited, Barings Australia Pty Ltd, Barings Japan Limited, Baring Asset Management Limited, Baring International Investment Limited, Baring Fund Managers Limited, Baring International Fund Managers (Ireland) Limited, Baring Asset Management (Asia) Limited, Baring SICE (Taiwan) Limited, Baring Asset Management Switzerland Sarl, Baring Asset Management Korea Limited, and Barings Singapore Pte. Ltd. each are affiliated financial service companies owned by Barings LLC (each, individually, an “Affiliate”). Some Affiliates may act as an introducer or distributor of the products and services of some others and may be paid a fee for doing so.

NO OFFER: The document is for informational purposes only and is not an offer or solicitation for the purchase or sale of any financial instrument or service in any jurisdiction. The material herein was prepared without any consideration of the investment objectives, financial situation or particular needs of anyone who may receive it. This document is not, and must not be treated as, investment advice, an investment recommendation, investment research, or a recommendation about the suitability or appropriateness of any security, commodity, investment, or particular investment strategy, and must not be construed as a projection or prediction.

Unless otherwise mentioned, the views contained in this document are those of Barings. These views are made in good faith in relation to the facts known at the time of preparation and are subject to change without notice. Individual portfolio management teams may hold different views than the views expressed herein and may make different investment decisions for different clients. Parts of this document may be based on information received from sources we believe to be reliable. Although every effort is taken to ensure that the information contained in this document is accurate, Barings makes no representation or warranty, express or implied, regarding the accuracy, completeness or adequacy of the information.

Any service, security, investment or product outlined in this document may not be suitable for a prospective investor or available in their jurisdiction.

Copyright and Trademark

Copyright © 2026 Barings. Information in this document may be used for your own personal use, but may not be altered, reproduced or distributed without Barings’ consent.

The BARINGS name and logo design are trademarks of Barings and are registered in U.S. Patent and Trademark Office and in other countries around the world. All rights are reserved.

Share this post

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor

Register

Contacts


Image
Logo

Barings is a $500 billion* global alternative asset manager that partners with institutional, insurance and wealth clients and supports leading businesses with flexible financing solutions. The firm, a subsidiary of MassMutual with a minority investment from MS&AD, seeks to deliver excess returns by leveraging its global scale and capabilities across credit, real assets, capital solutions and emerging markets.

*As of September 30, 2026
 

Ilena Coyle
Head of North American Insurance and Intermediary  
ilena.coyle@barings.com
973-271-2400

www.barings.com
 
300 South Tryon St, Suite 2500,
Charlotte, NC 28202


View the contributor page

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor .

Create an account

Already have an account ? Sign in

Ѐ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ѝ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С ΄ ΅ Ά · Έ Ή Ί Ό Ύ Ώ ΐ Α Β Γ Δ Ε Ζ Η Θ Ι Κ Λ Μ Ν Ξ Ο Π Ρ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С Т У Ф Х Ц Ч Ш Ā ā Ă ă Ą ą Ć ć Ĉ ĉ Ċ ċ Č č Ď ď Đ đ Ē ē Ĕ ĕ Ė fi fl œ æ ß