Shelter Growth Capital Partners -

Commercial Real Estate Mortgage Market Commentary 1H2026

ShelterGrowthFeatured

Market Backdrop

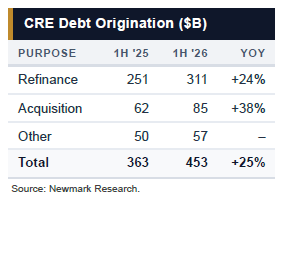
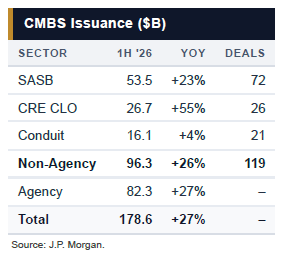
Origination and issuance were the story of the first half in commercial real estate (CRE) debt. Newmark Research estimates national CRE debt origination volume at $453 billion for the first half (up 25% year-over-year and 42% ahead of the 2017–2019 average), with acquisition financing (+38%) growing faster than refinancing (+24%). Securitized supply kept pace. Non-agency CMBS issuance reached $96 billion across 119 deals, 26% ahead of the same period in 2025, with single-asset/single-borrower (SASB) deals leading at $54 billion. CRE CLO, the vehicle most directly tied to financing bridge loans, grew fastest, up 55% year-over-year to $27 billion across 26 deals. Agency CMBS added roughly $82 billion, up 27%, as Freddie Mac, Fannie Mae and Ginnie Mae remained the dominant channel for stabilized multifamily lending. Total CMBS supply across agency and non-agency reached $179 billion, 27% ahead of last year.

The maturity wall is a durable source of demand. With roughly $2.1 trillion of CRE debt maturing over the next several years, we expect refinancing and bridge demand to stay elevated well beyond 2026, a tailwind for the direct bridge lending strategies at the center of our platform.

Image
Table
Image
Table

Bridge Lending

The lending recovery is broad-based but multifamily-led. Conditions for direct bridge lending improved through the first half of 2026, with transaction and origination activity recovering off 2024–25 lows and originations up across every major property type, led by multifamily, industrial and retail. Multifamily alone reached $191 billion, up 26% year-over-year and more than 40% of all CRE debt origination. Across the market, private and non-bank lenders continue to take share: lending by non-bank financial firms ran 54% above first-half 2025 levels. Our own pipeline followed a similar pattern, with volume across all property types up roughly 40% year-over-year and the majority of it multifamily.

Image
Table


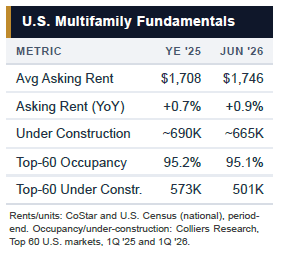
Supply and demand are moving back into balance. Multifamily occupancy across the Top 60 markets held steady near 95.1% in the first quarter, while the multifamily construction pipeline came down from its peak. Demand for multifamily continues to strengthen, with more than 279,000 units absorbed nationally in the first half (the second-highest first-half total on record). Annual inventory growth slowed to a 26-quarter low. Asking rents are positive nationally at +0.9% per CoStar, while effective rents (inclusive of concessions) remain negative at -0.2% per Newmark Research, as concessions stay elevated. That decline has narrowed for two consecutive quarters, and forecasts point to national rent growth returning to positive territory by the fourth quarter. Multifamily cap rates have also stabilized near the mid-5% range nationally, keeping exit and refinancing markets orderly for stabilizing bridge collateral.

Industrial is following a similar supply-and-demand path, with vacancy easing from its 7.6% peak to 7.4%, asking rents up 3.7% year-over-year, and no 60-day-plus delinquencies in either the CRE CLO or SASB universe.

Image
Table
Image
Table

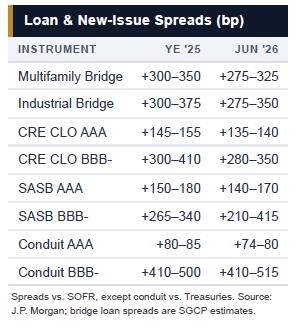
Asset and liability spreads both tightened. We are seeing multifamily bridge loans at 65% to 70% loan-to-value trade 20 to 30 basis points tighter than at the start of the year, with industrial spreads moving similarly. While tighter asset spreads compress new-money yields on the loans we originate, financing spreads have tightened materially alongside them. Warehouse advance rates on bridge loans are competitive at 75% to 80%, and financing spreads have tightened to the SOFR plus 130 to 150 basis point range on most collateral, from SOFR plus 160 to 190 basis points at the start of the year. Securitization markets showed similar strength. New issue CRE CLO AAA spreads moved 10 to 15 basis points tighter through the half, with full-stack execution providing around 87% to 88% advance term financing, equating to equity yields in the teens.

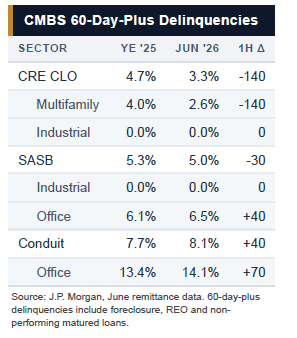
The stress is legacy vintage, not systemic risk. For a disciplined lender, concentrated stress is an opportunity. The securitized market offers the cleanest observable read on how bridge loans are actually performing, and it shows credit that is stable in aggregate but sharply bifurcated underneath. Sixty-day-plus delinquencies ended the half at 3.3% in CRE CLO (the closest analogue to our loans, down 140 basis points) against 5.0% in SASB and 8.1% in conduit. Office remains the primary driver of delinquencies in both conduit and SASB. Multifamily is the more instructive case, splitting by vintage rather than property type. Multifamily CMBS delinquencies of 7.15% (Colliers/Trepp, first quarter) trace overwhelmingly to the over-levered, floating-rate loans originated at peak pricing in 2021–2022. CRE CLO multifamily, the pool most representative of loans underwritten to today’s more conservative standards, fell to just 2.6%, also down 140 basis points over the half.
 

“Refinancing pressure is creating selective entry points, rather than broad operating distress, supporting a more targeted investment environment.”
— Colliers Research, Q1 2026 U.S. Multifamily Report


Institutional capital is responding to this dynamic: debt fund managers raised a record $34 billion in 2025, per Newmark Research, as CRE debt continues to screen as attractively valued relative to other fixed-income and equity alternatives.

CRE Activity at Shelter Growth Capital Partners

Since 2016, SGCP has originated $3.4 billion across more than 130 bridge loan transactions, with zero realized principal losses. We target loan sizes of $15 million to $75 million, with a focus on multifamily, industrial and select retail and hotel opportunities. Highlights of our commercial loan activity year to date:

  • Concentrated our first-half originations exclusively in multifamily bridge loans, at a weighted-average coupon of roughly SOFR plus 330 basis points, a weighted-average stabilized debt yield of 8.3%, and a stabilized loan-to-value of 69%, well inside the stressed 2021–2022 cohort described above.
  • Sourced an active pipeline across all four of those property types, with multiple loan applications signed, targeting spreads of SOFR plus 275 to 375 basis points, squarely the segment of the market where private and non-bank lenders are gaining the most share.
  • Continued ramping a new investment vehicle and, market conditions permitting, could look to issue a new CRE CLO around year-end or early next year.
  • Advanced marketing of a potential private securitization of seasoned CRE loan collateral.

Outlook

The outlook is positive, with the forces behind the increased activity in the first half appearing durable. Borrower demand is set by roughly $2.1 trillion of maturities still ahead and a recovering acquisition market, where first-half investment sales rose 31% year-over-year to the best first half since 2022, with industrial up 51%. The lender base itself has continued to reshape in favor of private and non-bank capital. Collateral fundamentals in the property types we favor are improving as the multifamily supply wave passes, and while loan spreads have compressed, financing markets have moved tighter alongside them, preserving attractive opportunities. The stress that remains is vintage-specific: delinquencies are in office and in the over-levered 2021–2022 multifamily cohort, while recently underwritten bridge collateral performs significantly better. We continue to favor bridge whole loan risk as the best risk-adjusted return in CRE debt. We are actively growing our separately managed accounts and commingled vehicles to pursue it, and we welcome the opportunity to discuss participation.

Image
Table


READ MORE FROM Shelter Growth Capital Partners


This communication is for information purposes only and shall not constitute an offer to sell or the solicitation of any offer to buy interests in any product managed by Shelter Growth Capital Partners LLC. This presentation in and of itself should not form the basis for any investment decision. Financial instruments and investment opportunities discussed or referenced herein may not be suitable for all investors, and potential investors must make an independent assessment of the appropriateness of any transaction in light of their own objectives and circumstances, including the possible risk and benefits of entering into such a transaction. An investor could lose all or a substantial amount of his or her investment and there is no guarantee that any investment objective will be achieved. Returns generated from an investment may not adequately compensate investors for the business and financial risks assumed. While all information prepared in this presentation is believed to be accurate, Shelter Growth has no obligation to update, modify or amend this presentation or notify readers of any changes or inaccuracies. Past performance is no guarantee of future results. Any projections, market outlooks or estimates in the presentation are forward-looking statements and are based upon certain assumptions. Other events which were not taken into account may occur and may significantly affect the returns or performance of an investment. Targeted returns are no guarantee of future performance and are based on our current perspective of future economic and market conditions. Future operating results may change based on changes in credit spreads, regulations impacting our operations, and economic forecasts. We have modeled these targeted returns based on our analysis of market growth, current/anticipated business capabilities and market counterparty appetite for our products. We cannot control every variable, and returns may not meet our anticipated targets. The information herein has not been provided in a fiduciary capacity, and it is not intended to be, and should not be considered, impartial investment advice. Data is as of June 30, 2026.

Share this post

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor

Register

Contacts


Image
Shelter-Growth-logo


Shelter Growth Capital Partners is a real estate credit focused, SEC-registered investment manager dedicated to building and managing diversified portfolios of residential and commercial real estate-related loans and securities. Shelter Growth’s clients benefit from the firm’s in-house direct lending platform which has acquired over $22 billion of residential and commercial real estate loans life-to-date. We believe that direct access to strong credit borrowers is essential to fully capitalize on the investment opportunities in residential and commercial real estate credit. We work with insurers to maximize risk-based capital returns in customized SMAs and other vehicles to meet desired risk/return metrics, providing a turnkey solution to efficiently access these sectors.

Scott Barringer 
Head of Business Development
sbarringer@sgcp.com 
Office: (203) 355-6109

750 Washington Boulevard
10th Floor Stamford
CT 06901


View the contributor page

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor .

Create an account

Already have an account ? Sign in

Ѐ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ѝ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С ΄ ΅ Ά · Έ Ή Ί Ό Ύ Ώ ΐ Α Β Γ Δ Ε Ζ Η Θ Ι Κ Λ Μ Ν Ξ Ο Π Ρ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С Т У Ф Х Ц Ч Ш Ā ā Ă ă Ą ą Ć ć Ĉ ĉ Ċ ċ Č č Ď ď Đ đ Ē ē Ĕ ĕ Ė fi fl œ æ ß