
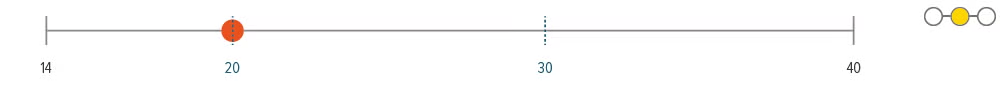
Voya Investment Management -

Fixed Income Perspectives: Themes for the Second Half of 2026

VoyaFeatured

Sean Banai, CFA - Head of Multi-Sector Fixed Income


The back half of 2026 may hinge on six themes: AI spending, uneven growth, labor supply, sticky inflation, uneasy central banks, and volatile bond markets.

1 The AI supercycle is both a growth engine and a policy flashpoint. 

The AI buildout looks set to keep going through the back half of 2026, with capital spending still firm and the market still willing to give companies time to prove the case. But that patience will not last forever. Investors will start asking harder questions if spending slows, productivity gains stay thin, or revenue and profit fail to follow. Regulation and politics could become the bigger swing factor, which leaves growth expectations intact for now but raises the odds of sharper repricing if the story starts to crack.

2 U.S. growth firms even as consumer exhaustion sets in. 

The U.S. still appears better positioned than much of the world, with AI investment, fiscal spending, and generational wealth transfer helping keep growth near trend. The weak link is the consumer. Real income pressure could limit how much farther spending can carry the expansion, while overseas growth may run softer as higher commodity prices offset the effect of stimulus and defense outlays. That split favors markets tied to U.S. resilience, but it also leaves less room for disappointment in sectors priced for a stronger global backdrop.

3 Labor stabilizes but remains structurally tight. 

Payroll growth will stabilize as tariff uncertainty and fears around AI-related job loss start to fade. Even so, labor supply remains constrained by demographics and tighter immigration policy, which should limit downside wage pressure even if hiring slows. The result may be a labor market that feels calmer without becoming soft, with bigger differences across industries. That keeps the inflation picture messy and makes it harder to predict the next move from the Federal Reserve.

4 For U.S. inflation, 3% is the new 2%. 

Inflation may avoid another breakout, but it’s also unlikely to return to the Fed’s 2% target anytime soon. Recurring supply shocks in a more fragmented global economy, along with persistent demand from price insensitive AI spending and upperincome consumers, could keep it hovering near 3%. Offsets from shelter, wage dynamics, and the fading effect of tariff-related price increases should help keep it from moving much higher. That argues for a market where yields stay elevated, and duration still needs to be handled with care.

5 Central banks more tolerant but inspire less certainty. 

The Fed may be willing to sit with inflation running somewhat above target if it sees the pressure as commodity-led and wage growth as contained. Even then, the policy picture may not feel settled as differences inside the FOMC complicate the policy narrative. Meanwhile other developed-market central banks with narrower mandates will likely manage a shallower hiking cycle. Rising debt burdens and fears of sustainability are also pushing central banks across developed markets toward closer coordination between monetary and fiscal policy. That leaves rates markets more exposed to policy friction, headline risk, and sudden changes in tone than a calm policy backdrop would suggest.

6 Income is back, but so is volatility. 

Higher yields still offer real income in fixed income markets, which changes the starting point for investors in a good way. The catch is that spreads remain tight, leaving less cushion if growth stumbles or policy mistakes pile up. At the same time, AI spending tied to energy, defense, and supplychain self-sufficiency could still lift earnings while also planting the seeds for excess and poor capital allocation in parts of the market. That makes broad exposure less forgiving and puts more weight on sector choices and security selection across public and private markets.
 

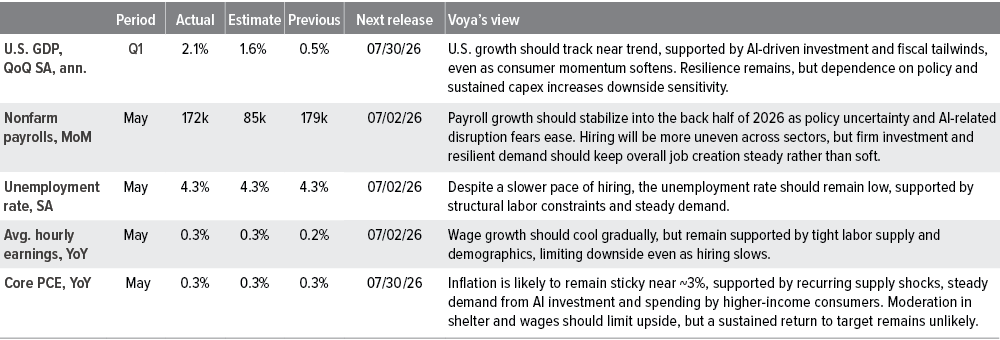
U.S. macro summary
Image
Table showing U.S. macro summary

As of 06/24/26. Source: Bloomberg, FactSet, Voya IM.
 

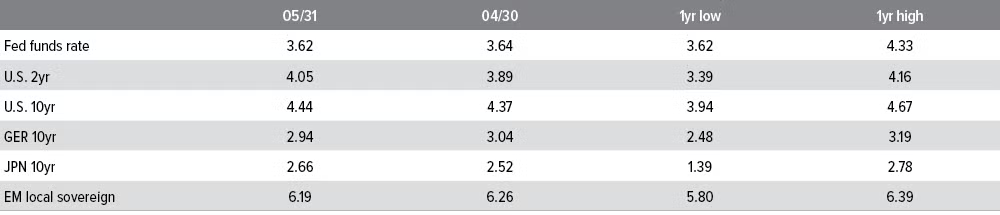
Yields (%)
Image
Table showing yields

As of 05/31/26. Sources: Bloomberg, J.P. Morgan, Factset, Voya IM. SA: Seasonally adjusted. PCE: Personal consumption expenditures.
 

Sector outlooks

Image
Legend


Investment grade corporates
Image
Fig4
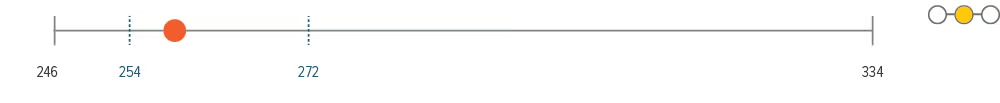
  • IG spreads are back near year-to-date and multidecade tights after grinding tighter in May. Valuation (not fundamentals) remains the main constraint on adding broad risk. 
  • Demand remains supported by higher all-in yields, especially out the curve, while May supply was heavy but manageable and fund flows rebounded. 
  • Fundamentals remain strong, but rate volatility, geopolitical risk, and inflation surprises could quickly undermine tight spreads.
     
High yield corporates
Image
Fig5
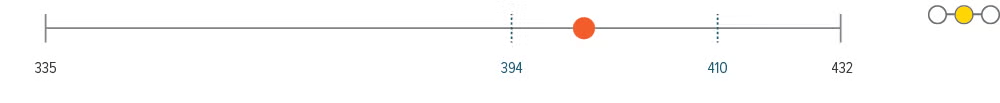
  • High yield fundamentals and technicals remain supportive, although we see limited opportunity with average spreads hovering near all-time tights, leaving carry as the primary driver of total returns. 
  • We believe downside risk remains manageable, with defaults expected to remain low against a favorable earnings backdrop. However, we note increased dispersion across lower-quality and more cyclical credits. 
  • Positioning should favor durable business models and higher-quality BB/B risk while remaining selective in CCCs and cyclicals.
     
Senior loans
Image
Fig6
  • Senior loans remain supported by strong demand technicals, especially collateralized loan obligation (CLO) formation and recovering retail inflows, even as issuer dispersion stays elevated. 
  • Fundamentals are stable overall, with leverage and coverage still reasonable, but liability management exercises (LMEs) and downgrade risk remain concentrated in weaker low-B issuers.
  • Security selection remains critical as AI disruption, geopolitical risk, and consumer-sensitive sectors drive performance dispersion.
     
Securitized credit
Image
Fig7
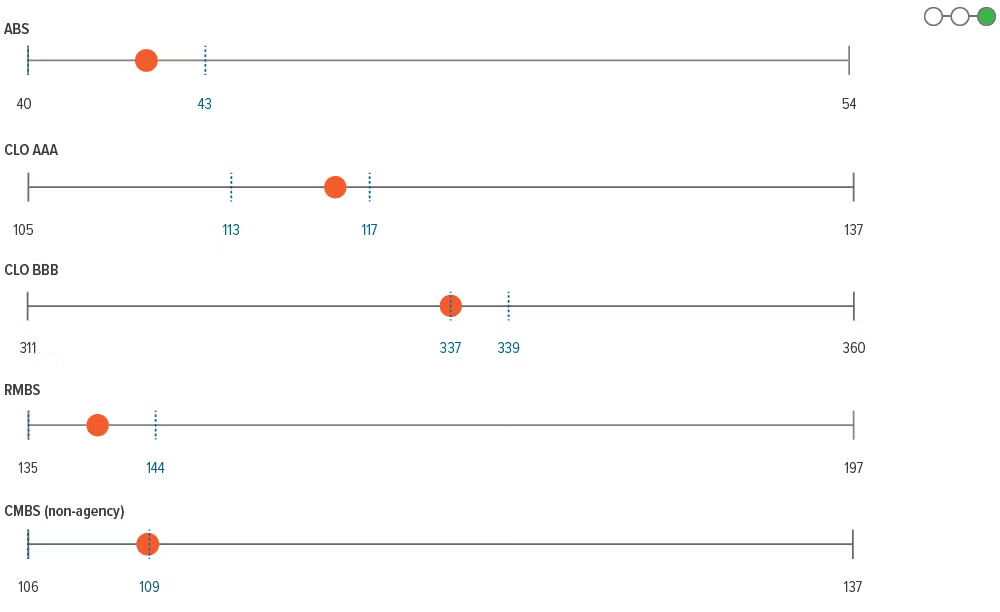
  • Securitized credit remains the most differentiated opportunity set, but the outlook is uneven across subsectors: mortgage credit and CMBS look constructive, CLOs remain cautious, and consumer asset-backed securities (ABS) are more challenged. 
  • Mortgage credit benefits from strong housing collateral, accumulated home-price appreciation, and still-open investor allocations. However, higher rates can weaken some convexity benefits by reducing the likelihood that discounted mortgage bonds get paid back sooner through refinancing or turnover, which would otherwise help investors recover principal more quickly and reinvest at attractive yields. 
  • CMBS still offers selective spread premium as fundamentals improve and supply becomes more manageable, while CLO and ABS positioning should stay selective given AI, private credit, and consumer stress risks.
     
Agency mortgages
Image
Fig8
  • Agency mortgage-backed security performance remains tied primarily to rate volatility, policy headlines, and technical flows rather than a deterioration in mortgage fundamentals. 
  • Suppressed prepayments and limited net supply remain supportive, while demand could improve on potential regulatory clarity and buying by government sponsored enterprises (GSEs). 
  • Near-term risks include disappointing GSE purchase execution, bank and overseas buyer hesitation, Fed reinvestment into Treasuries, and renewed rate volatility shocks.
     
Emerging market debt
Image
Fig9
  • Emerging market hard currency debt has recovered with positive flows and tighter spreads, but high oil prices, geopolitical risk, and tighter financial conditions leave the macro backdrop fragile. 
  • Absolute yields remain attractive, but sovereign and corporate spreads are already close to historically tight levels, limiting valuation upside. 
  • Positioning should stay focused on higher-quality EM corporates and quasis, with caution on sovereigns, cyclicals, oil importers, and economies vulnerable to renewed stagflation pressure.
     

READ MORE FROM VOYA INVESTMENT MANAGEMENT


Image
Fig10


IM5628629
1 As of 06/15/26. Source: Voya IM. Data show UST nominal spread for current coupon.

Index information: Investors cannot invest directly in an index. Index returns do not reflect fees, brokerage commissions, taxes or other expenses of investing. U.S. Agg: Bloomberg U.S. Aggregate Bond Index. Treasuries: Bloomberg U.S. Treasury Index. IG corp: Bloomberg Corporate Bond Index. MBS: Bloomberg Securitized – U.S. MBS Index. CMBS: Bloomberg CMBS ERISA Eligible Index. HY corp: Bloomberg U.S. Corporate High Yield: 2% Issuer Cap Index. EM $ Sov: J.P. Morgan EMBI Global Diversified Index. EM local sov: J.P. Morgan GBI-EM Index.

Past performance does not guarantee future results. This market insight has been prepared by Voya Investment Management for informational purposes. Nothing contained herein should be construed as (i) an offer to sell or solicitation of an offer to buy any security or (ii) a recommendation as to the advisability of investing in, purchasing, or selling any security. Any opinions expressed herein reflect our judgment and are subject to change. Certain statements contained herein may represent future expectations or other forward-looking statements that are based on management’s current views and assumptions and involve known and unknown risks and uncertainties that could cause actual results, performance, or events to differ materially from those expressed or implied in such statements. Actual results, performance, or events may differ materially from those in such statements due to, without limitation, (1) general economic conditions, (2) performance of financial markets, (3) interest rate levels, (4) increasing levels of loan defaults, (5) changes in laws and regulations, and (6) changes in the policies of governments and/or regulatory authorities. The opinions, views, and information expressed in this commentary regarding holdings are subject to change without notice. The information provided regarding holdings is not a recommendation to buy or sell any security. Fund holdings are fluid and are subject to daily change based on market conditions and other factors.

Share this post

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor

Register

Contacts


Image
01-voya-stacked-sidebar

Voya Investment Management is a leading authority in insurance asset management, bringing the capabilities of a large institutional investment manager with proprietary insurance balance sheets to small and medium sized insurance companies and key strategic partnerships. As the manager of a large and complex proprietary life insurance balance sheet, we extend every resource committed to that undertaking to our third-party clients. Our deep insurance resources and expertise, investment process and infrastructure built especially for regulated balance sheets, and our high touch client engagement model are all key differentiators versus our competitors.

Voya Investment Management ("Voya IM") delivers actively managed public and private market solutions that drive differentiated outcomes for clients worldwide. Our team of 300+ investment professionals manages $353 billion in assets as of March 31, 2026.1 We excel at partnering with clients to understand their needs and address challenges in innovative ways, drawing on extensive expertise across fixed income, equity, multi-asset, and alternative strategies.​

Andrew Terry
Managing Director
Head of Insurance Solutions Group
Andrew.Terry@voya.com
203-984-2609
 

View the contributor page
 

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor .

Create an account

Already have an account ? Sign in

Ѐ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ѝ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С ΄ ΅ Ά · Έ Ή Ί Ό Ύ Ώ ΐ Α Β Γ Δ Ε Ζ Η Θ Ι Κ Λ Μ Ν Ξ Ο Π Ρ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С Т У Ф Х Ц Ч Ш Ā ā Ă ă Ą ą Ć ć Ĉ ĉ Ċ ċ Č č Ď ď Đ đ Ē ē Ĕ ĕ Ė fi fl œ æ ß