First Eagle Investments -

Securitization in Focus—August 2026

FirstEagleFeatured

Douglas Gimple
Client Portfolio Manager


Headlines
  • Credit Card Asset-Backed Securities (ABS). In aggregate, credit card ABS reached $12.3 billion year to date versus $16.5 billion for all of 2025. The sector has seen two debut issuers this year—Robinhood and Prosper. Prosper is new to credit card ABS but has been in the unsecured consumer loan ABS sector since 2017. Charge-offs dropped 0.28% year over year to 1.90% for August, holding below 2% for the second consecutive month and the lowest since the stimulus-fueled pandemic lows in late 2023.1,2
  • Auto ABS. The lower-income segment of the market remains the weakest performing from an absolute delinquency perspective, while the higher-income segment has seen the largest year-over-year increase in delinquencies. More recently, however, deterioration rates have converged across income groups. Even as lower income borrowers are expected to continue deteriorating, the pace of deterioration for higher-end borrowers should decelerate.3
  • Personal Loan ABS. Consumer debt growth has slowed, while underwriting standards remain relatively tight. Delinquency trends appear more stable than headline credit bureau data may suggest.

It is important to note that personal loans are unsecured and carry additional risk relative to other forms of consumer credit. In financial stress scenarios, consumers tend to prioritize payments for auto loans to avoid repossession and credit cards to preserve revolving liquidity. Personal loans can vary considerably based on credit quality (prime versus non-prime), method (online, brick and mortar or point of sale), loan term and promotional structure.

Throughout 2Q26 earnings calls, ABS sponsors reported constructive results due to strong growth in origination, while others noted improving credit trends. Management teams continued to highlight pressure on lower-income borrowers and non-prime segments but noted that newer vintages (under tighter underwriting standards) are generally outperforming older cohorts.

Exhibit 1: Despite ongoing geopolitical and fiscal uncertainty, spreads across risk assets remain tight (in basis points)

 Credit Card Asset-Backed SecuritiesAuto Asset-Backed SecuritiesNon-Agency Commercial Mortgage-Backed SecuritiesAgency Residential Mortgage-Backed SecuritiesInvestment Grade CorporatesHigh Yield Corporates
Dec 31 202532.553.7121.021.877.4268.1
Jan 31 202631.148.8111.715.772.5263.6
Feb 28 202629.949.3113.620.983.7292.8
Mar 31 202632.453.9119.123.988.7320.2
Apr 30 202632.451.6113.321.379.4274.7
May 31 202629.947.2108.922.071.3256.2
Jun 30 202626.244.3109.524.573.5264.4
Jul 31 202625.142.9110.831.077.8279.4
Aug 31 202628.144.7109.929.377.1260.9
       
YTD Minimum23.741.5106.013.870.6247.7
YTD Maximum34.256.4121.031.092.7338.1
YTD Average29.648.3112.122.077.3273.0
10-year Minimum16.224.169.47.070.6247.7
10-year Maximum263.1378.3347.9132.3381.11,099.1
10-year Average40.559.1123.637.5109.5371.2

Source: Bloomberg; data as of August 31, 2026.

 
Asset-Backed Securities Issuance4
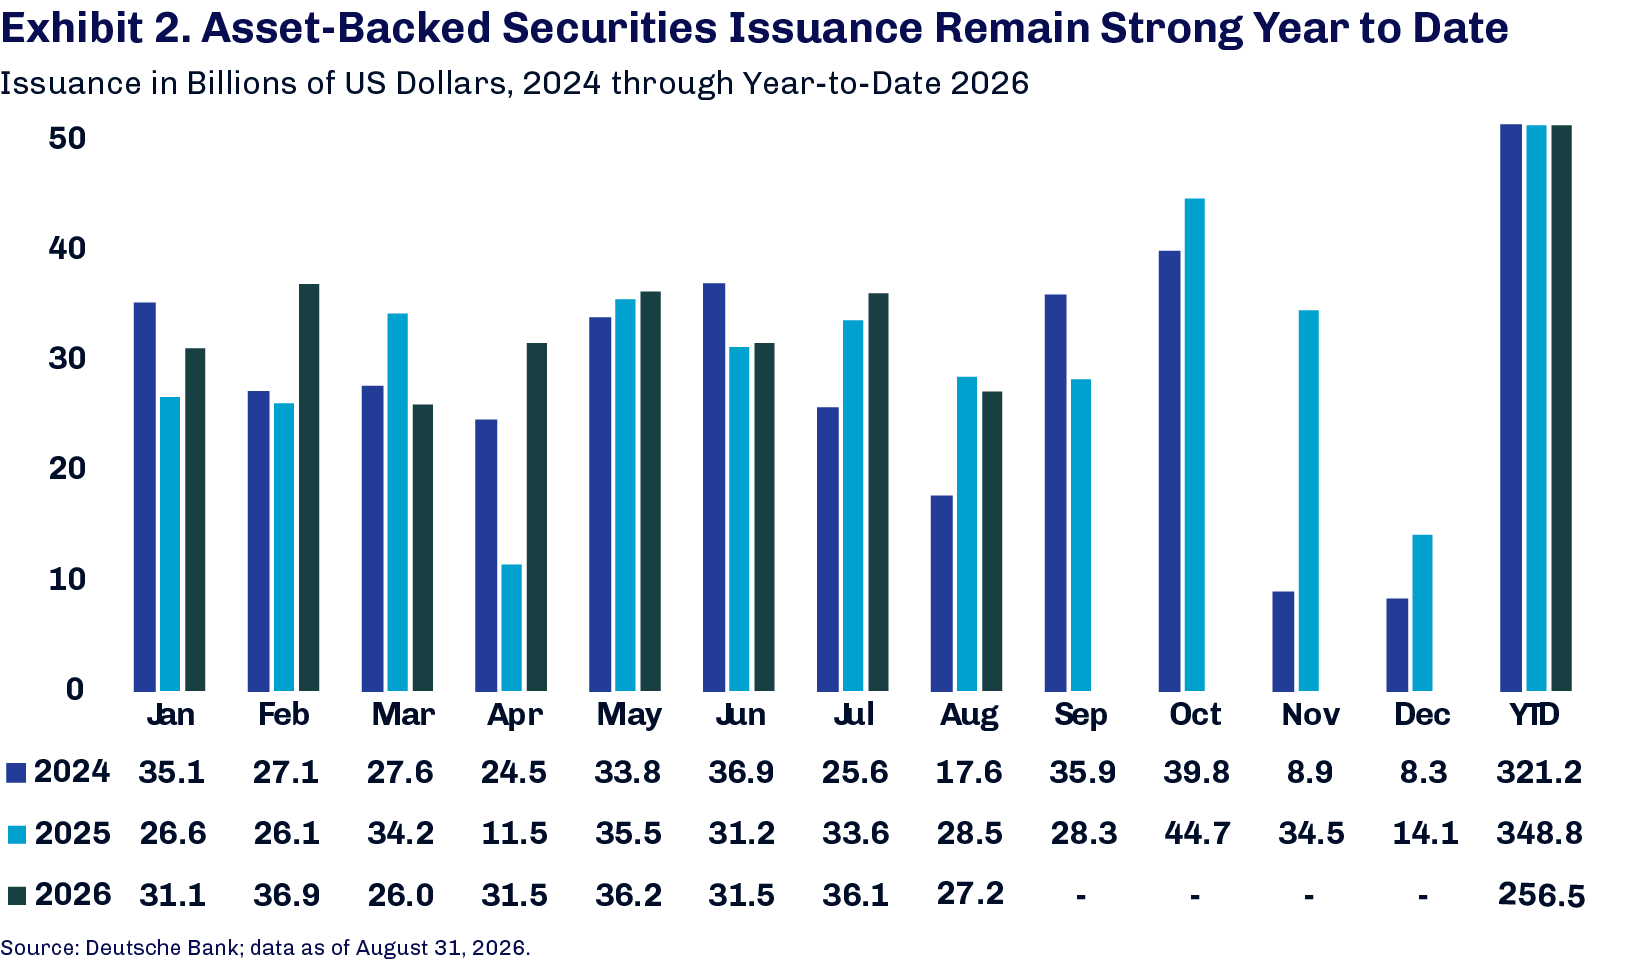
  • Issuance typically slows during the hot summer months, and August 2026 was no exception. After a torrid pace over the prior four months ($33.8 billion monthly average), issuance eased to $27.2 billion in August.
  • Despite the August slowdown, full-year issuance remains on pace to surpass both 2024 and 2025 levels, barring an unforeseen slowdown beyond the typical December slowdown.
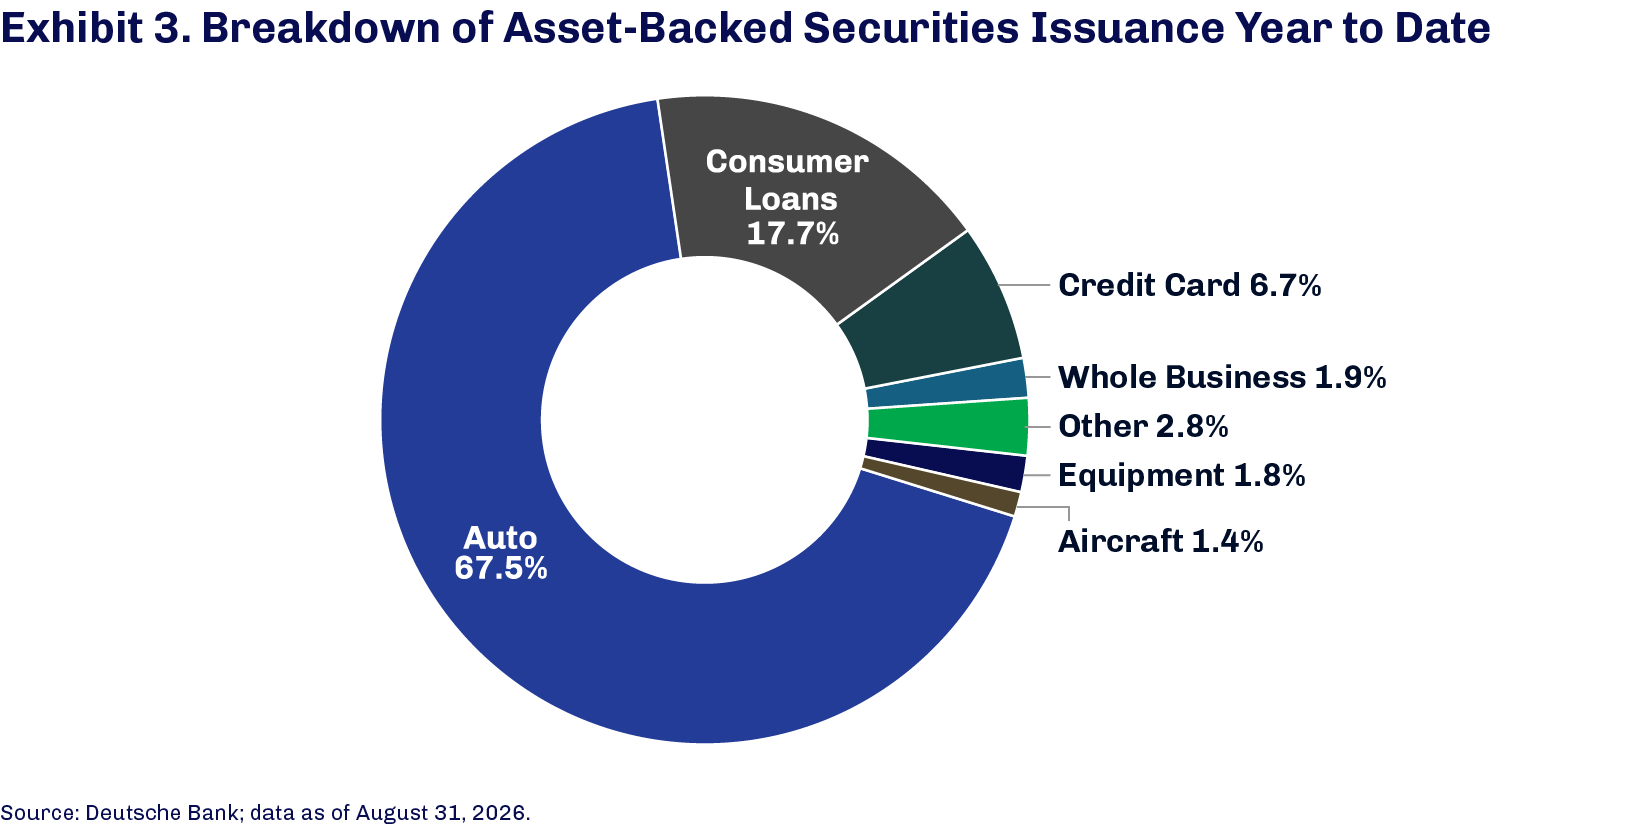
  • Auto ABS typically consists of roughly half of overall ABS issuance, but August was particularly auto heavy, with the sector representing 67.5% of issuance. Activity in several recently active areas of the market, including data centers and fiber, slowed during the month.
  • Although issuance trailed off in the second half of August, September is gearing up to be issuance heavy. Despite a late Labor Day (September 7), September could emerge as the busiest issuance month of the year.

First Eagle Investments Securitization in Focus August 2026 chart

First Eagle Investments Securitization in Focus August 2026 chart

Commercial Mortgage-Backed Securities (CMBS) Trends in August5

Sector trends

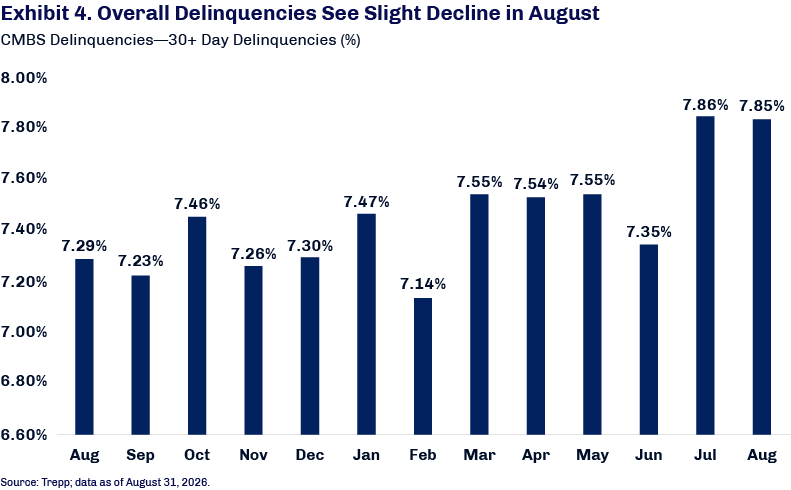
  • Overall delinquencies. -0.01% to 7.85%, continuing the fluctuating trend but at a greater clip than previous months.
  • Delinquency rate. Year over year +0.56% (7.29 % to 7.85%).
  • Serious delinquency rate. +0.12% month over month (7.57% to 7.69%). Represents the percentage of loans that are 60+ days delinquent, in foreclosure, real estate owned or non-performing.
  • The five largest newly delinquent loans included office towers in Chicago, Los Angeles and Washington, D.C., an office portfolio spanning Washington, D.C. and Northern Virginia, and a New Orleans hotel.

By property type level

  • Multifamily. Flat at 7.69%.
  • Office. +0.09% to 12.00% with loans exiting delinquency helping to offset poorly performing loans tied to an office complex in the Washington, D.C. and Northern Virginia area.
  • Lodging. +0.49% to 5.84%, marking the second consecutive month of increase, fueled by newly delinquent hotels in New Orleans and a national hotel portfolio.
  • Retail. +0.24% to 7.20% with newly delinquent regional malls outweighing loan cures from other malls that were brought back to performing status.
  • Industrials. +.01% only, to 1.14%.

First Eagle Investments Securitization in Focus August 2026 CMBS chart

Non-Agency Residential Mortgage-Backed Securities (RMBS)6

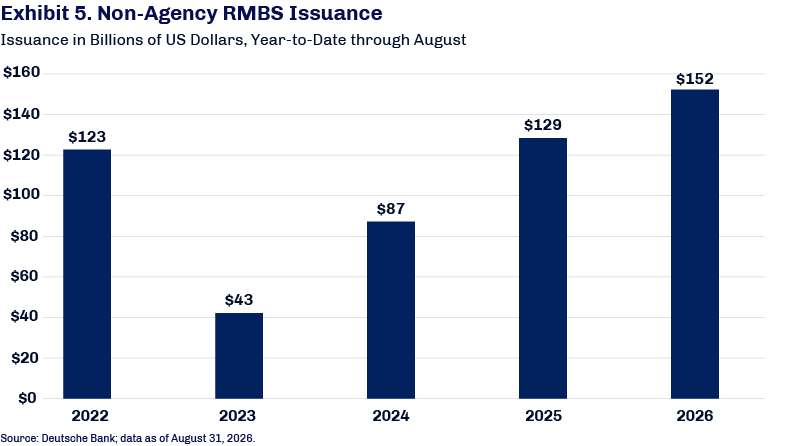
As in other areas of the securitized market, non-agency RMBS issuance typically slows in August. August’s issuance was slightly ahead of the prior months’ average level ($18.9 billion) as the market brought an additional $19.6 billion to market during the month. Despite the slowdown, the sector is on pace to surpass 2025’s $194 billion in issuance, though the specter of higher rates could temper activity.

First Eagle Investments Securitization in Focus August 2026 RMBS chart

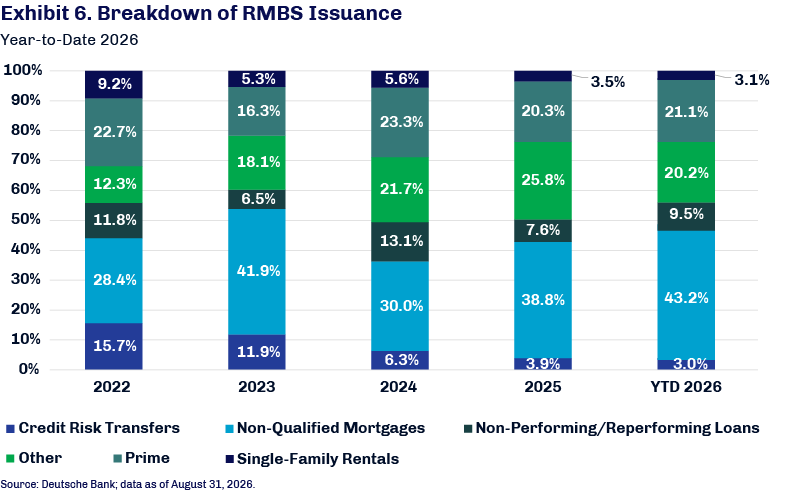
Non-qualified mortgage (QM) issuance market continues to dominate the market, accounting for roughly 43.2% of August issuance, slightly above levels since the beginning of the year. Non-QM loans offer greater flexibility in borrower eligibility and documentation requirements than mortgages meeting Consumer Financial Protection Bureau standards.

First Eagle Investments Securitization in Focus August 2026 RMBS chart


READ MORE FROM FIRST EAGLE INVESTMENTS

1 Prosper Marketplace Issuance Trust.
2 J.P. Morgan ABS Update; data as of August 31, 2026. 
3 Bank of America ABS Weekly; data as of August 31, 2026. 
4 Source: Deutsche Bank; data as of August 31, 2026.
5 Source: Trepp; data as of August 31, 2026.
6 Source: Deutsche Bank; data as of August 31, 2026.

The information contained in this material is provided by First Eagle Investment Management, LLC (“FEIM”) and its global subsidiaries (collectively, “First Eagle”). FEIM is an investment adviser registered with the US Securities and Exchange Commission (SEC). Registration with the SEC does not imply a certain level of skill or training.

This material is for informational purposes only and reflects prevailing conditions and the judgment of the author(s) as of the date of publication, all of which are subject to change. This material should not be relied upon as investment advice; it does not constitute a recommendation to buy or sell a security or other investment; and it is not intended to predict or depict the performance of any investment. This material is not being provided in a fiduciary capacity and is not intended to recommend any investment policy or investment strategy or consider the specific objectives or circumstances of any investor. We consider the information in this material to be accurate, but we do not represent that it is complete or should be relied upon as the sole source of appropriateness for investment.

Prospective investors should inform themselves and consult with an investment, tax or legal professional as to any applicable legal requirements, taxation and exchange control regulations in the countries of their citizenship, residence or domicile that may be relevant prior to investing.

This material does not constitute an offer or solicitation in any jurisdiction where or to any person to whom it would be unauthorized or unlawful to do so.

All investments involve the risk of loss of principal.

Investments in bonds are subject to interest-rate risk and can lose principal value when interest rates rise, while they typically increase their principal values when interest rates decline. Bonds are also subject to credit risk, in which the bond issuer may fail to pay interest and principal in a timely manner, or that negative perception of the issuer’s ability to make such payments may cause the price of that bond to decline.

Strategies whose investments are concentrated in a specific industry or sector may be subject to a higher degree of risk than funds whose investments are diversified and may not be suitable for all investors.

Diversification does not guarantee investment returns and does not eliminate the risk of loss.

Past performance does not guarantee future results, which may vary. The value of investments and the income derived from investments will fluctuate and can go down as well as up. A loss of principal may occur.

Spread typically is used to express the difference between two interest rates.

Mortgage-backed securities (MBS) are debt securities whose payments of principal and interest are backed by the cash flow generated by pools of mortgage loans.

Residential mortgage-backed securities (RMBS) are debt securities whose payments of principal and interest are backed by the cash flow generated by pools of residential mortgage loans.

Asset-backed securities (ABS) are debt securities whose payments of principal and interest are backed by the cash flow generated by pools of income-producing credit assets.

Commercial mortgage-backed securities (CMBS) are debt securities secured by cash flows from commercial real-estate mortgages.

Investment grade corporate bonds are debt securities issued by corporations perceived to have a relatively low risk of default.

High yield bonds (also called junk bonds) are bonds deemed by rating agencies to have a higher risk of default and thus offer investors a higher interest rate than investment grade bonds.

The information presented does not reflect the performance of any fund, strategy or account managed or serviced by First Eagle, and there is no guarantee that investors will experience the type of performance reflected. There is no guarantee that any market forecast set forth in this material will be realized. There is no guarantee that any historical trend referenced herein will be repeated in the future, and there is no way to predict precisely when such a trend will begin. The mention of specific securities is not a recommendation or solicitation to buy, sell or hold any particular security and should not be relied upon as investment advice.

Availability of the products or services described may be restricted by law in certain jurisdictions. This material may not be distributed, published or used by any person or entity in any jurisdiction or country where such distribution or use would be contrary to local law or regulation.

United Kingdom: Napier Park Global Capital Ltd. is authorized and regulated by the Financial Conduct Authority (FRN: 541427).

Middle East: This material is for information purposes only and has not been, and will not be, registered with or reviewed or approved by any regulator located in the Middle East. It does not constitute or form part of any marketing initiative, any offer to issue or sell, or any solicitation of any offer to subscribe to or purchase, any products, strategies or other services, nor shall it, or the fact of its distribution, form the basis of, or be relied on in connection with, any contract resulting therefrom. In the event that the recipient of this material wishes to receive further information regarding any products, strategies or other services, it shall specifically request the same in writing from an authorized financial adviser.

Canada: Pursuant to the international adviser registration exemption in National Instrument 31-103, First Eagle Investment Management, LLC. is informing you that: (i) First Eagle Investment Management, LLC. is not registered in Canada and is advising you in reliance upon an exemption from the adviser registration under National Instrument 31-103; (ii) First Eagle Investment Management, LLC’s jurisdiction of residence is New York, USA; (iii) there may be difficulty enforcing legal rights against First Eagle Investment Management, LLC. because it is a resident outside of Canada and all or substantially all of its assets may be situated outside of Canada.

FEF Distributors, LLC (“FEFD”) (SIPC), a limited purpose broker-dealer, distributes certain First Eagle products. FEFD does not provide services to any investor but rather provides services to its First Eagle affiliates. As such, when FEFD presents a fund, strategy or other product to a prospective investor, FEFD and its representatives do not determine whether an investment in the fund, strategy or other product is in the best interests of, or is otherwise beneficial or suitable for, the investor. No statement by FEFD should be construed as a recommendation. Investors should exercise their own judgment and/or consult with a financial professional to determine whether it is advisable for the investor to invest in any First Eagle fund, strategy or product.

First Eagle Investments is the brand name for First Eagle Investment Management, LLC and its subsidiary investment advisers. Diamond Hill is the brand name for Diamond Hill Capital Management, LLC, an investment adviser.

©2026 First Eagle Investment Management, LLC. All rights reserved.

Share this post

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor

Register

Contacts


Image
FEI-Stacked-Color-sidebar

First Eagle Investments is an independent, privately owned investment management firm headquartered in New York with approximately $217 billion in assets under management as of June 30, 2026.* Dedicated to providing prudent stewardship of client assets, the firm focuses on active, fundamental, and benchmark-agnostic investing, with a strong emphasis on downside mitigation. With over 15 years of experience managing assets on behalf of insurers, First Eagle is focused on meeting their unique portfolio and servicing needs through bespoke investment solutions and a dedicated insurance coverage team. The firm’s investment capabilities for the insurance market include alternative credit, fixed income, and global equities.
 

All figures related to assets under management (AUM) are preliminary figures based on management’s estimates and as such are subject to change. Some offerings may not be available in all jurisdictions.

As of 30-June-2026.

*The total AUM listed above represents the combined AUM and assets under advisement of First Eagle Investment Management, LLC, First Eagle Separate Account Management, LLC, Napier Park Global Capital (Napier Park), First Eagle Alternative Credit (FEAC), and Diamond Hill Capital Management, LLC as of 30-Jun-2026. It includes $3.1 billion in committed/non-fee-paying capital from Napier Park, inclusive of assets managed by RLM and CMV, and $0.8 billion in committed/non-fee-paying capital from FEAC. For CLO warehouses, AUM represents maximum commitment (loan par value). As of 5-Sep-2025, Napier Park and FEAC investment activities are unified under Napier Park’s brand and management. First Eagle Alternative Credit, LLC is a distinct registered investment advisor within the Napier Park platform, acting in sub-advisory capacity to a number of First Eagle’s registered funds.
 

Katie Cowan   
Head of Insurance Client Solutions
katie.cowan@firsteagle.com
(310) 893-2440
 

View the contributor page

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor .

Create an account

Already have an account ? Sign in

Ѐ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ѝ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С ΄ ΅ Ά · Έ Ή Ί Ό Ύ Ώ ΐ Α Β Γ Δ Ε Ζ Η Θ Ι Κ Λ Μ Ν Ξ Ο Π Ρ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С Т У Ф Х Ц Ч Ш Ā ā Ă ă Ą ą Ć ć Ĉ ĉ Ċ ċ Č č Ď ď Đ đ Ē ē Ĕ ĕ Ė fi fl œ æ ß