Pioneer Investments -

Agency Mortgage-Backed Securities (MBS) Market

IAUM_Article_Banner_Pioneer-MBS-Oct26_1004x422

Tyler Patla
Managing Director, Deputy Director of Core Fixed Income, Director of Agency Mortgages
Portfolio Manager


Agency MBS Recouped Much of September’s Selloff

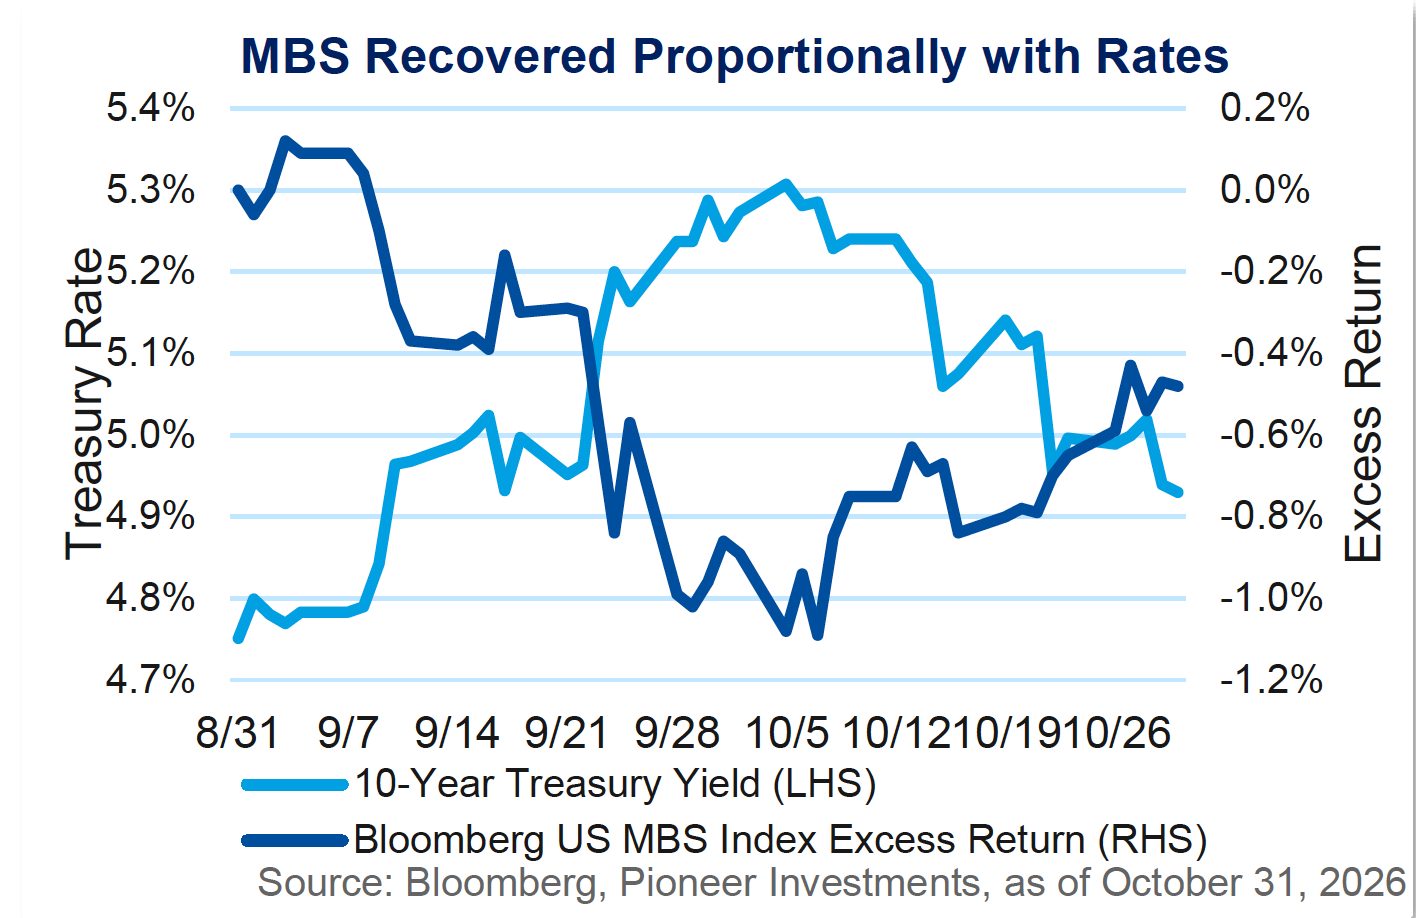
In October, agency MBS recouped much of September’s losses as a flight-to-quality rally pulled Treasury yields sharply lower. A selloff in technology shares on weak AI-related earnings, along with stress in French sovereign debt, then drove a near-parallel bull move. The 2-, 5-, and 10-year yields fell 30bp, 37bp, and 36bp, the 10-year’s largest monthly decline since late 2023. This came even though the Fed held rates steady on October 28 with two dissents in favor of a hike. The ICE BofA MOVE Index of implied rate volatility eased from 110 to 100.

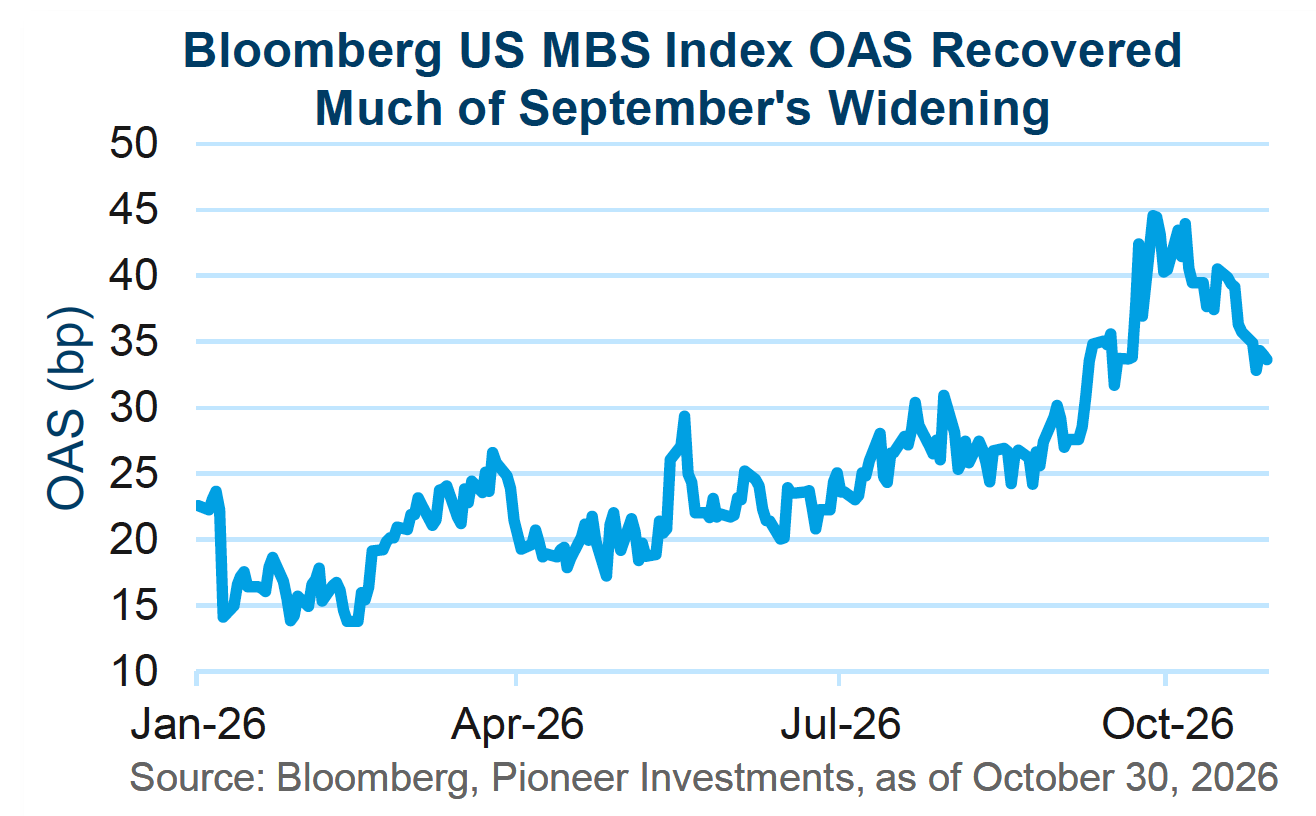
The Bloomberg US MBS Index returned +3.07%, its best month since December 2023 and enough to recover most of September’s -3.38%. That reflected a +0.48% excess return to Treasuries as sector OAS tightened by 9bp to +34bp, reversing roughly two-thirds of September’s widening. In production coupons, the tightening came largely from lower option cost rather than compression versus the curve: current-coupon OAS tightened 13bp while its zero-volatility spread was unchanged near 107bp. Lower coupons, which constitute a majority of the sector, tightened by roughly equal amounts in nominal and option-adjusted terms. Performance was consistent across 30-year Fannie Mae, 30-year Ginnie Mae, and 15-year bonds, which delivered between +45bp and +48bp of excess return. The index’s duration shortened by only 0.03 years to 5.68, reversing little of September’s extension. MBS outperformed investment-grade corporates, which returned +2.16% but lagged duration-matched Treasuries by 59bp as OAS widened 10bp to +90bp amid weakness in AI-linked credits.

Chart comparing 10-year Treasury yields and Bloomberg US MBS Index excess returns during September and October 2026.

Source: Bloomberg, Pioneer Investments, as of October 31, 2026.

In this issue, we will analyze a new executive order targeting mortgage affordability, examine the actions of Fannie Mae and Freddie Mac during September’s distress, and update our outlook at new valuations.

Executive Order Targeted Housing Costs with Minimal Short-Term Impact

The White House signed an executive order on October 22 titled “Decreasing Housing Costs for the American People.” It seeks to reduce housing costs for homeowners by curbing excessive title insurance, waiving appraisals, income reverification, and other documentation for some refinancings, proactively canceling mortgage insurance, lowering rates on government direct loan programs, and establishing a task force on manufactured housing. While the messaging is logical, our analysis suggests the impact will be minimal. The cumulative changes would save the average new mortgage borrower about 7bp on their mortgage rate. Because only 2% of borrowers have rates that are refinanceable at current market levels, these changes are unlikely to save a meaningful proportion of existing homeowners an appreciable amount of money unless interest rates fall 200bp or more. Additionally, increased borrower responsiveness could cheapen current-coupon MBS proportionally, causing mortgage rates to rise by an offsetting amount.

Agencies Added $11.7bn in MBS in September

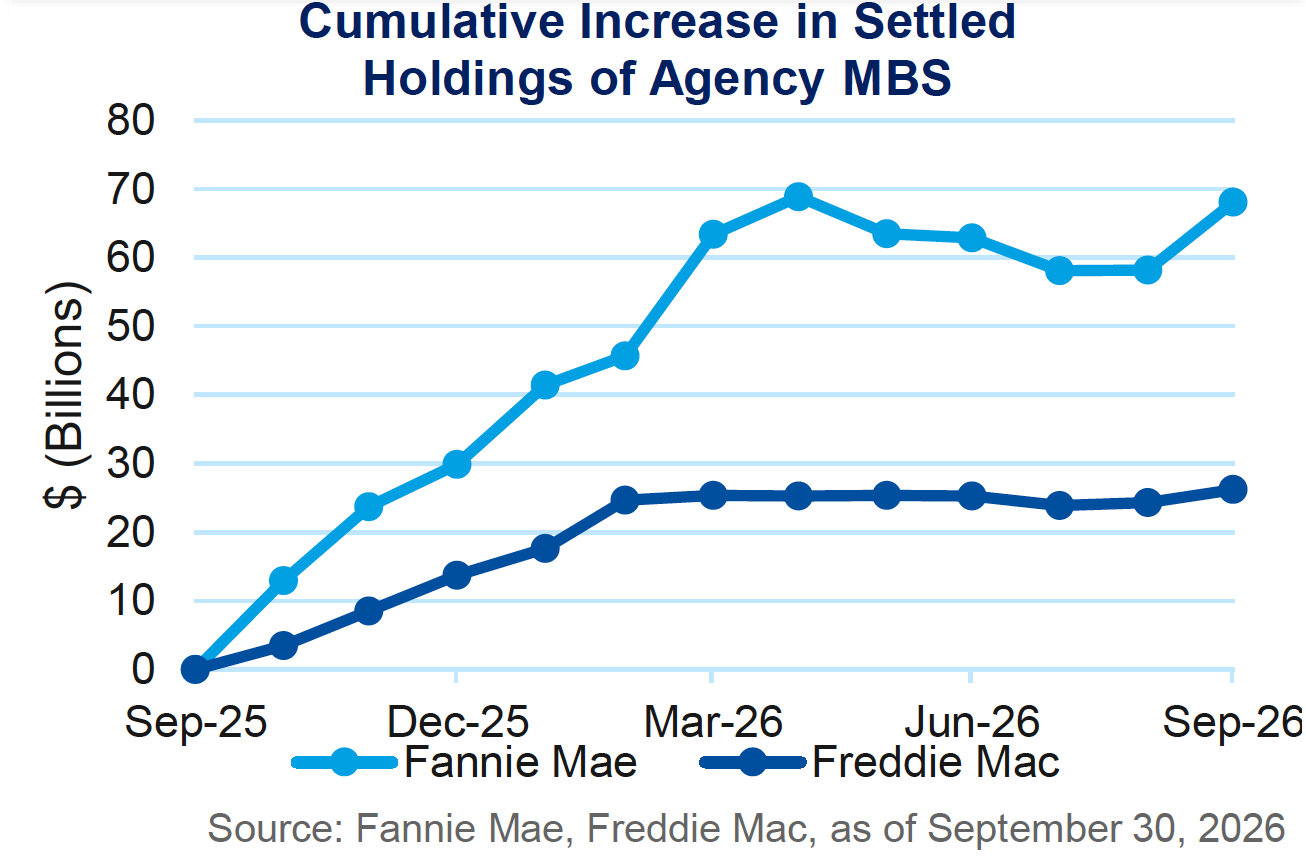
Fannie Mae and Freddie Mac curiously allowed their mortgage portfolios to shrink between April and August, until FHFA Director Pulte stated on September 18 that the agencies were “beginning to buy even more, large quantities” of MBS amid the widening selloff. In October, monthly disclosures revealed the numbers: Fannie Mae added $9.9bn, while Freddie Mac added $1.8bn. These numbers could effectively be larger because they reflect only settled bonds, not forward contracts, but the agencies are still nowhere near the pace that would be necessary to fulfill the directive the Trump administration made in January 2026: the combined portfolios sit over $110bn below the cap they would have presumably hit at the end of 2026. With limited messaging outside of occasional social media posts and monthly reporting, and with political impetus potentially waning after the midterm elections, we would not rely on agency purchases as a meaningful source of demand going forward, absent new information.

Outlook: Value Restored, Technicals Still Conflicting

After September’s widening pushed agency MBS spreads well through the wide end of their range, October’s rate reversal helped bring the agency MBS market most of the way back. The pass-through from macro headlines to MBS spreads has remained a function of valuations, technicals, and fundamentals, and while we anticipated an eventual reversal, the timeline was faster than we expected. This returns us to dynamics we have weighed for most of 2026.

Valuations: Mortgage OAS to Treasuries has been tighter 43% of the time over the past 10 years, while, following recent weakness, the OAS on the Bloomberg US Corporate Index has been tighter 29% of the time. October’s divergent price action narrowed the gap in both OAS and year-to-date excess return terms, making agency MBS less compelling (but still compelling) relative to corporate bonds. Meanwhile, OAS to swaps, which sits wider because of negative swap spreads, tightened by 11bp to +71bp, almost 20bp above its average over the past decade; many potential buyers of MBS have historically hedged with swaps and view MBS through this metric.

Chart showing the Bloomberg US MBS Index option-adjusted spread recovering much of September's widening during October 2026.

Source: Bloomberg, Pioneer Investments, as of October 30, 2026.

Technicals: Regulators are reportedly preparing to finalize the revised Basel III capital rules in December, which could allow banks to make up for a lack of purchases in recent years. However, while current carry relative to interest on reserve balances (IORB) remains near recent highs, a more hawkish projected Fed path has lowered forward projections of banks’ net interest margin on MBS. Similarly, while currency-hedged carry for overseas investors is relatively strong, higher projected Fed funds rates increase projected hedging costs. Consistent with FHFA Director Pulte’s mid-September pronouncement, the agencies collectively added about $12bn in securities in September, though future buying remains uncertain despite meaningful room under the asset cap. Mortgage real estate investment trust (mREIT) price-to-book ratios have remained resilient despite recent deterioration in book values from September’s widening, allowing some mREITs to raise capital via stock issuance rather than deleverage.

Chart comparing the cumulative increase in settled agency mortgage-backed securities holdings by Fannie Mae and Freddie Mac.

Source: Fannie Mae, Freddie Mac, as of September 30, 2026.

Fundamentals: AI advancements and isolated prepayment data have continued to suggest more efficient refinancing the next time mortgage rates fall, with the potential for streamline refinancing in conventional loans that could meaningfully accelerate cheapest-to-deliver prepayments. However, that risk remains distant: despite October’s tightening rally, the proportion of borrowers with meaningful refinance incentive rose only from 1% to 2%. October’s executive order targeting mortgage origination costs is dwarfed by the gap between outstanding and current mortgage rates. With prepayment risk remote, extension is the more relevant near-term consideration. If faster speeds do eventually arise, the scope for security selection increases, as does the potential for dislocations from changing government policies.

In both dedicated mortgage and multi-sector accounts, we have taken profits on some, but not all, of the tactical additions to agency MBS made amid September’s widening. September demonstrated that macro forces, hedging needs, and indiscriminate de-risking can overwhelm support from real money and relative value investors in the short run, but October illustrated that demand can return quickly if dynamics reverse. We remain dynamic in our allocations and ready to react if valuations are driven beyond relative value expectations via systematic hedging, forced selling, or opportunistic buying.

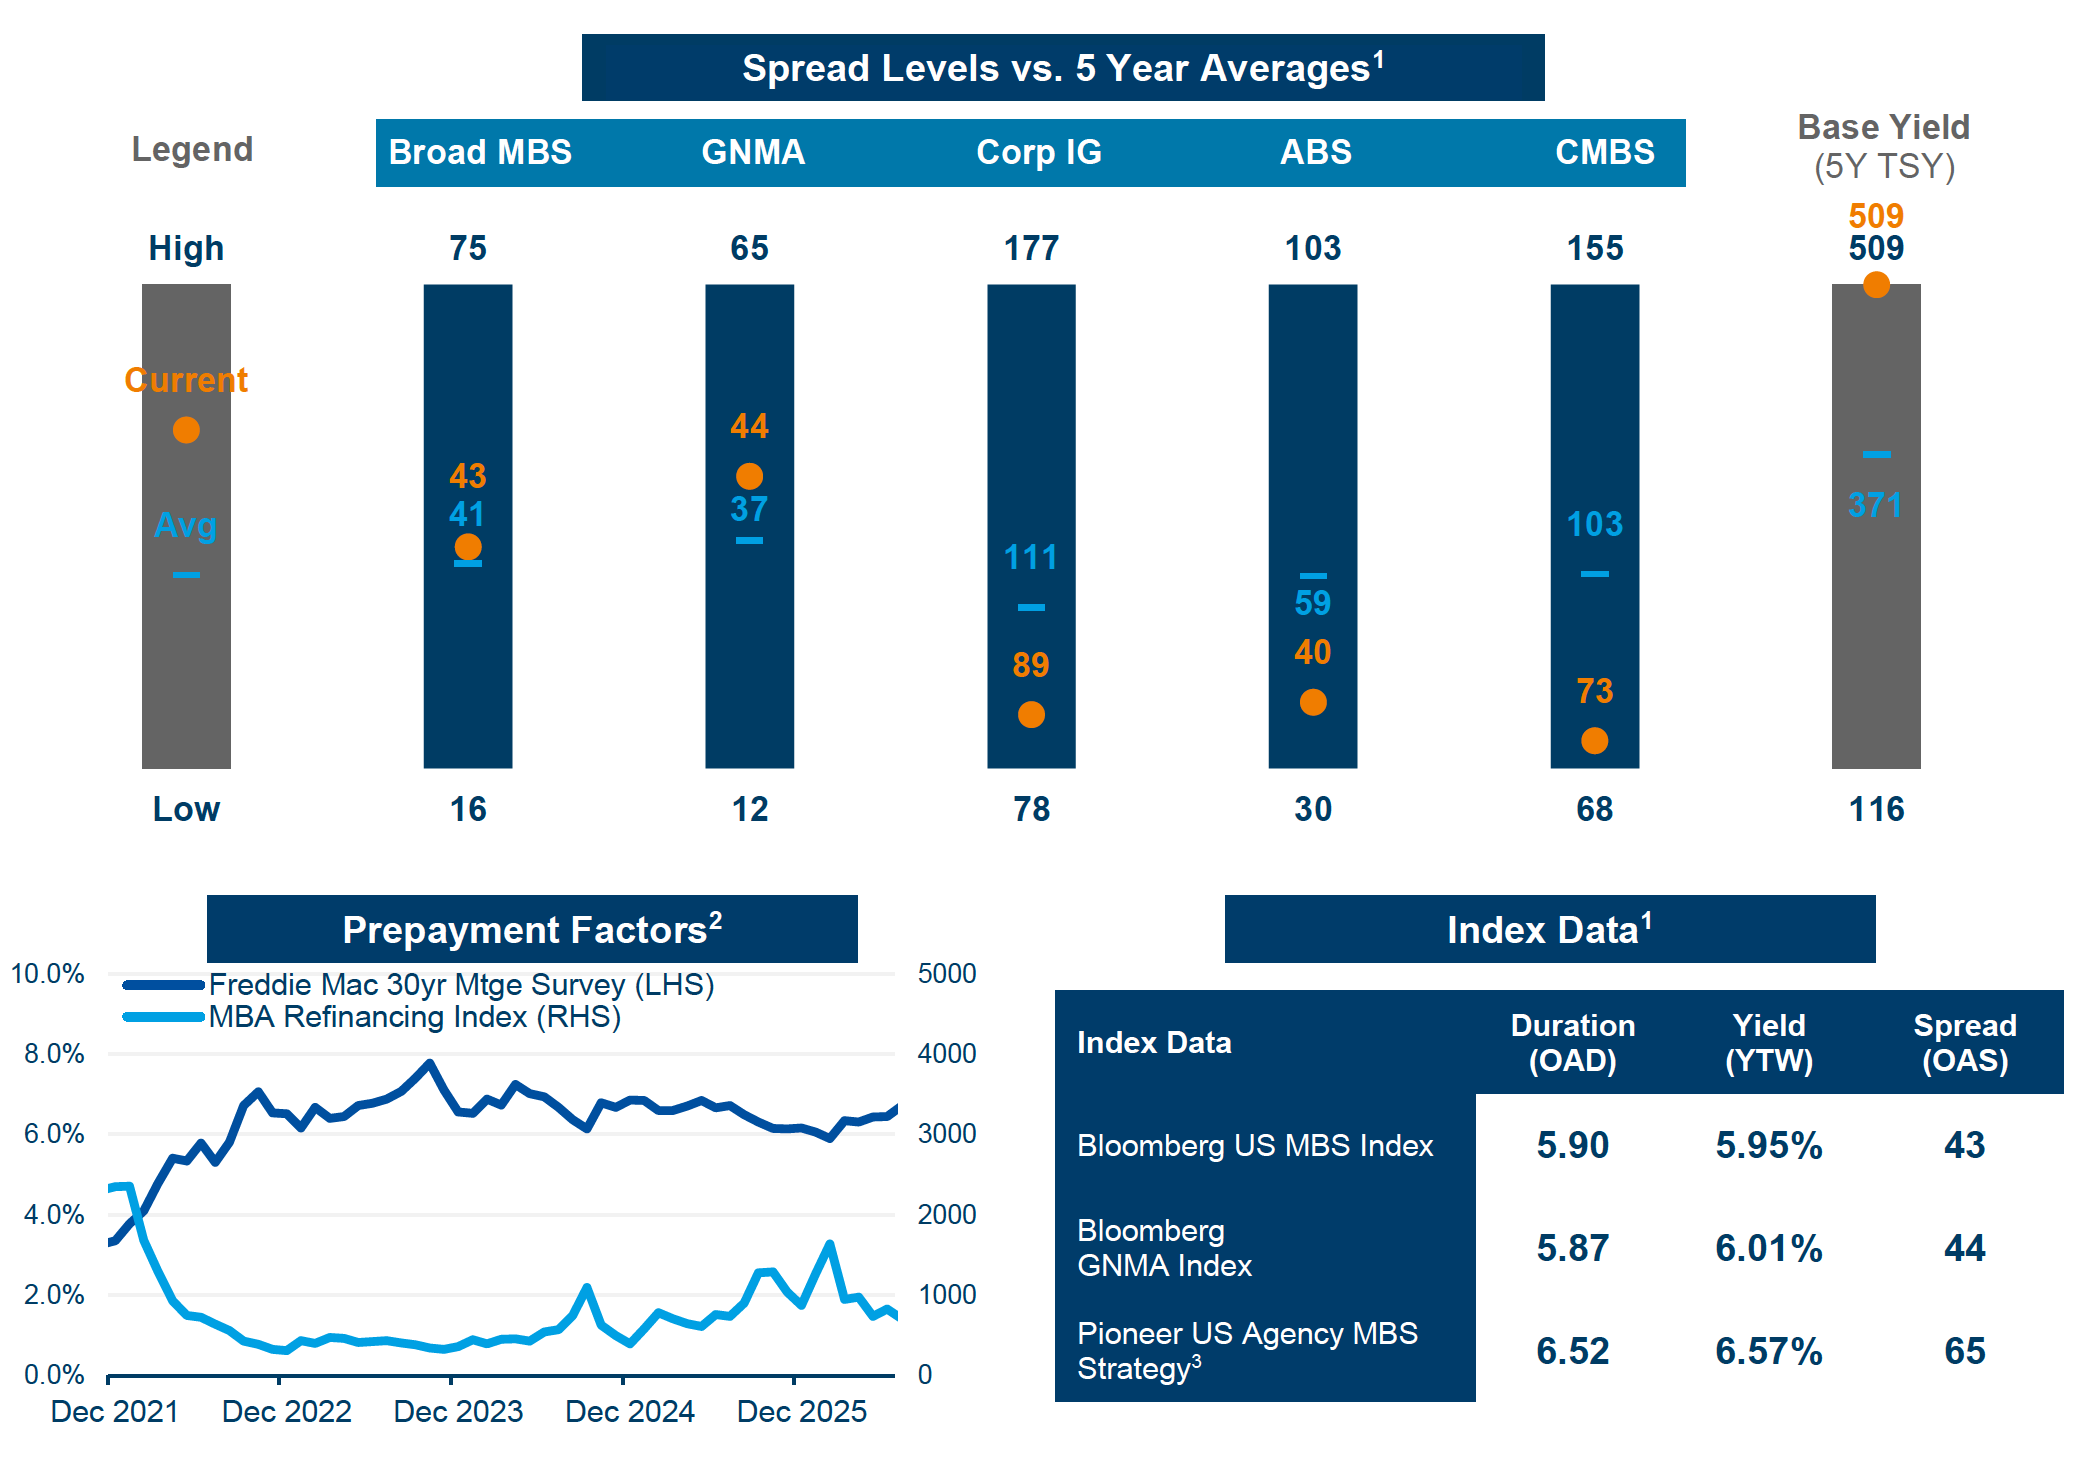
Securitized Market Dashboard

Pioneer Investments securitized market dashboard comparing mortgage-backed security spreads, prepayment factors and index characteristics.

Source: Bloomberg, as of September 30, 2026.

1. Index Data: Bloomberg US MBS Index, Bloomberg GNMA Index, Bloomberg US Aggregate Corporate Average OAS, Bloomberg US Investment Grade ABS Index, Bloomberg US Investment Grade CMBS Index.

2. S&P/Experian First Mortgage Default Index, MBA Refinance Index.

3. The characteristics are of the representative account (gross, USD) in the US Agency MBS composite. Gross-of-fees returns are presented before management and custodial fees but after any transaction costs.

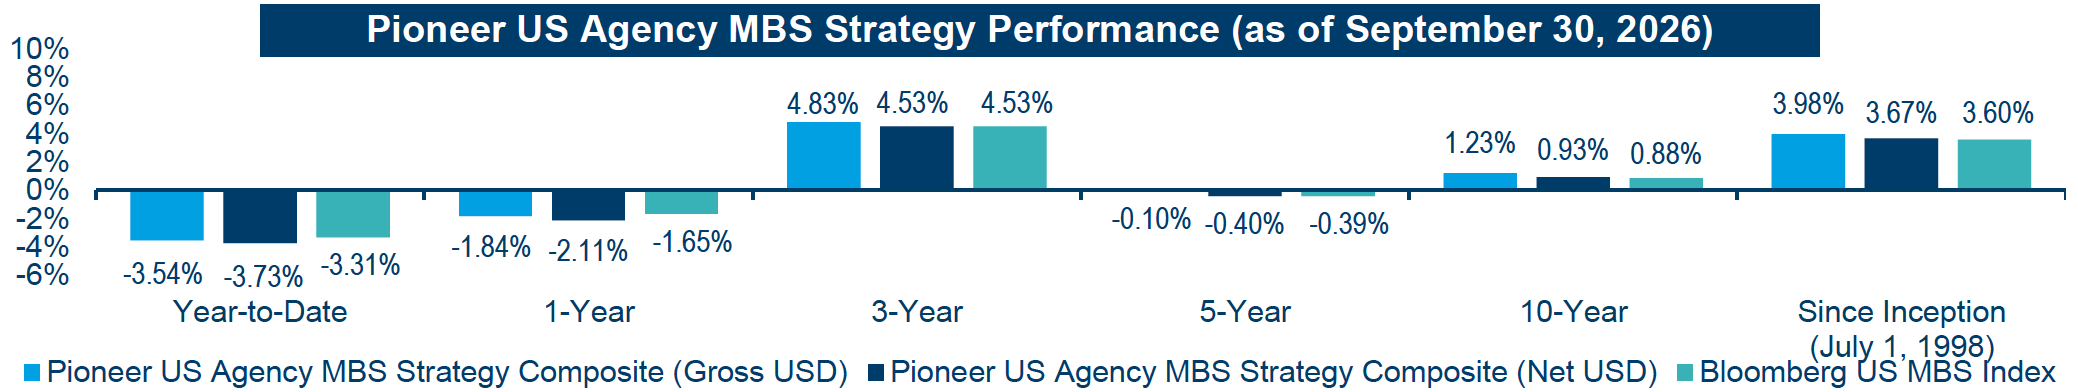
Pioneer US Agency MBS Strategy Performance (as of September 30, 2026)

Bar chart showing Pioneer US Agency MBS Strategy gross and net performance compared with the Bloomberg US MBS Index across multiple periods.

Source: Pioneer Investments, as of September 30, 2026.

Performance prior to April 1, 2025, occurred while the portfolio management team was affiliated with a prior firm. Such members of the portfolio management team were responsible for investment decisions at the prior firm and the decision-making process has remained intact.

Returns greater than one year are annualized. Returns are expressed in US dollars and reflect the reinvestment of dividends and other earnings. Composite and benchmark returns are presented net of non-reclaimable withholding taxes. Gross-of-fees returns are presented before management and custodial fees but after all transaction costs. Net-of-fees returns are calculated by deducting 1/12 of the highest tier of the standard fee schedule in effect for the period noted (the model fee). The composite model fee for each period is either the highest tier of the current fee schedule or a higher value, whichever is required to ensure the model composite net-of-fee return is lower than or equal to the composite net-of-fee return calculated using actual fees. Actual fees may vary depending on, among other things, the applicable fee schedule and portfolio size.

Please refer to the GIPS® Report for additional information.

Past performance is no guarantee of future results.

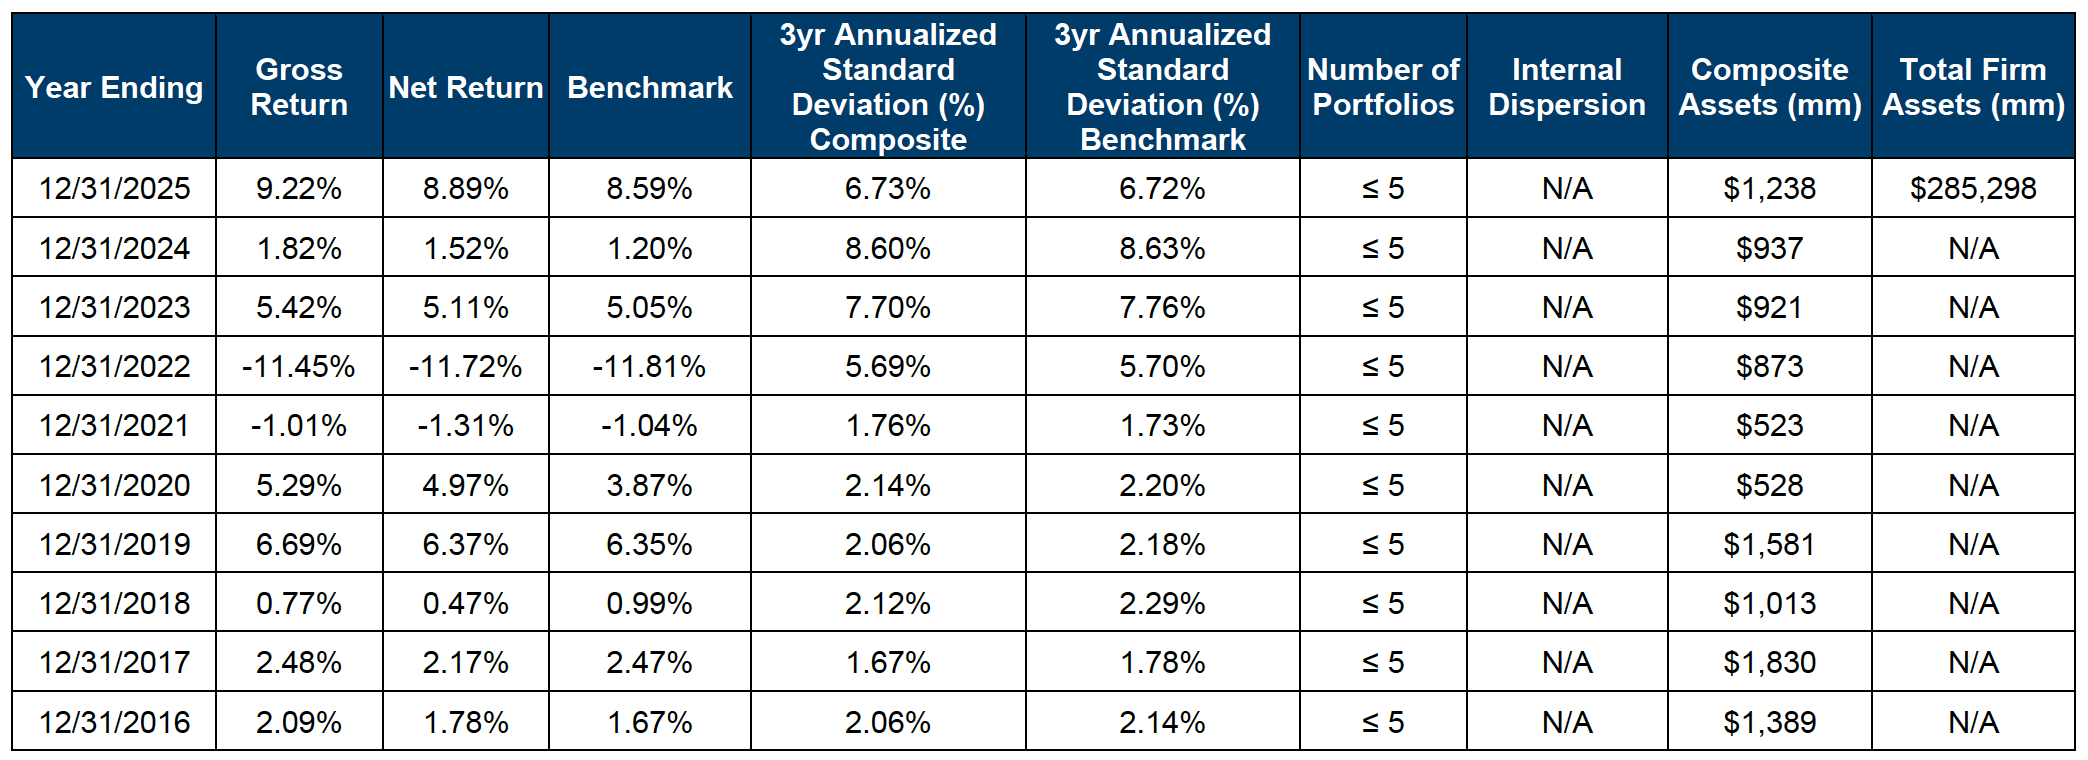
Pioneer US Agency MBS Strategy Composite Performance

Pioneer US Agency MBS Strategy composite performance table showing annual gross returns, net returns, benchmark returns, standard deviation and composite assets.

Firm assets prior to 2018 are shown as "N/A" above as the composite was not part of the firm.


READ MORE FROM PIONEER INVESTMENTS


Disclosures

All investing involves risk, including the possible loss of principal. An investment should be made with an understanding of the risks involved with owning a particular security or asset class.

Unless otherwise stated, all information contained in this document is from Pioneer Investments, a Victory Capital ® Investment Franchise. The views expressed in this presentation are those of Pioneer Investments as of the date noted, and are subject to change at any time. These views should not be relied upon as investment advice, as securities recommendations, or as an indication of trading intent on behalf of any of portfolio.

The services and any securities described in this document may not be registered for sale with the relevant authority in your jurisdiction and may not be regulated or supervised by any governmental or similar authority in your jurisdiction. Where unregistered, they may not be sold or offered except in the circumstances permitted by law. Pioneer Investments is not making any representation nor does this document constitute a representation with respect to (i) the eligibility of any recipients of this document to acquire any securities or any services described herein in any jurisdiction or (ii) the eligibility of any recipients of this document to receive this document in any jurisdiction. If you are in doubt about the content of this document or your eligibility, you should obtain independent professional advice.

Sector allocations are subject to change. Holdings are subject to change and should not be construed as investment advice or a recommendation to buy, sell, or hold any security. Information relating to portfolio holdings is based on the representative account in the composite and may vary for other accounts in the strategy due to asset size, client guidelines and other factors.

Indexes are unmanaged; their returns include reinvestment of dividends and other income but do not reflect management fees, transaction costs or expenses. It is not possible to invest directly in an index. Past performance does not guarantee future results.

Advisory Services offered by Victory Capital Management Inc.

©2026 Victory Capital Management Inc.

GIPS® Composite Notes

1. Victory Capital Management Inc. claims compliance with the Global Investment Performance Standards (GIPS®) and has prepared and presented this report in compliance with the GIPS standards. Victory Capital Management Inc. has been independently verified for the periods January 1,2001 through December 31, 2025. The verification report is available upon request. A firm that claims compliance with the GIPS standards must establish policies and procedures for complying with all the applicable requirements of the GIPS standards. Verification provides assurance on whether the firm's policies and procedures related to composite and pooled fund maintenance, as well as the calculation, presentation, and distribution of performance, have been designed in compliance with the GIPS standards and have been implemented on a firm-wide basis. Verification does not provide assurance on the accuracy of any specific performance report.

2. Victory Capital Management Inc. (VCM) is a diversified global investment adviser registered under the Investment Advisers Act of 1940 and comprises multiple investment franchises: Integrity Asset Management, New Energy Capital Partners, Pioneer Investments, RS Investments, Sycamore Capital, Trivalent Investments, Victory Income Investors, WestEnd Advisors and the Victory Capital Solutions Platform. RS Investments and Sophus Capital became a part of the VCM GIPS firm effective January 1, 2017; Victory Income Investors, effective July 1, 2019; THB Asset Management, effective March 1, 2021; New Energy Capital effective November 1, 2021; Amundi Asset Management US, Inc. (renamed to “Pioneer Investments”), effective April 1, 2025; and WestEnd Advisors, effective September 30, 2026. Effective July 1, 2025, Newbridge Asset Management, Sophus Capital, and THB Asset Management are no longer part of the GIPS firm. Effective December 1, 2025, Munder Capital Management is no longer part of the GIPS firm.

3. The Pioneer US Agency MBS Strategy seeks to produce returns in excess of the index by actively managing a portfolio consisting primarily of agency mortgage-backed securities. The composite creation date is June 1998, and the composite inception date is July 1, 1998. The benchmark of the composite is the Bloomberg US MBS Index.

4. The benchmark of the composite is the Bloomberg US MBS Index. The Bloomberg US MBS Index tracks fixed-rate, agency mortgage-backed pass-through securities guaranteed by Ginnie Mae, Fannie Mae, and Freddie Mac (FHLMC), making it a key benchmark for this segment of the U.S. bond market. It groups securities into generic pools by program, coupon, and vintage, focusing on investment-grade bonds with at least $1 billion outstanding and a weighted average maturity over one year, providing broad exposure to government-backed MBS. The benchmark returns are provided to represent the investment environment existing during the time periods shown and are not covered by the report of independent verifiers. For comparison purposes, the index is fully invested, which includes the reinvestment of income. The returns have been taken from a published source and do not include any transaction fees, management fees, or other costs.

5. The internal dispersion of annual returns is measured by the standard deviation of asset-weighted gross returns of accounts included in the composite for the full year. If less than six portfolios are included in the composite for the full year, no dispersion measure is presented, as it is not considered meaningful (N/M). The three-year annualized ex-post standard deviation measures the variability of the composite’s gross returns, and the benchmark returns over the preceding 36-month period. It is not required to be presented for annual periods when a full three years of composite performance is not yet available.

6. Composite and benchmark returns are presented net of non-reclaimable withholding taxes. Gross-of-fees returns are presented before management and custodial fees but after all transaction costs. Net-of-fees returns are calculated by deducting 1/12 of the highest tier of the standard fee schedule in effect for the period noted (the model fee). The composite model fee for each period is either the highest tier of the current fee schedule or a higher value, whichever is required to ensure the model composite net-of-fee return is lower than or equal to the composite net-of-fee return calculated using actual fees. Actual fees may vary depending on, among other things, the applicable fee schedule and portfolio size. The complete fee schedule for this product is:

Market ValueAnnual Fee
First $50,000,0000.25%
Next $50,000,0000.225%
Next $100,000,0000.20%
Above $200,000,0000.15%

7. Valuations and returns are stated in U.S. dollars. Past performance should not be considered indicative of future performance. Composite returns reflect the reinvestment of dividends and other earnings. A list of broad distribution pooled funds, composite and limited distribution pooled fund descriptions and policies of valuing investments, calculating performance, and preparing GIPS Reports are available upon request. Registration with the SEC does not imply a certain level of skill or training.

8. The composite is managed by Pioneer Investments (formerly Amundi Asset Management US, Inc. Performance prior to April 2025 occurred while the team was affiliated with a prior firm. Such members of the portfolio management team were responsible for investment decisions at the prior firm, and the decision-making process has remained intact. The historical performance has been linked to performance earned at Victory Capital Management Inc.

9. GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein.

20261111-6099820

Share this post

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor

Register

Contacts


Image
Pioneer Stacked Logo FL


Pioneer Investments manages $160 billion in assets and has a long-standing history of innovation with deep expertise managing fixed income portfolios and creating customized solutions within the more opportunistic areas of the securitized market.

Pioneer Investments’ culture of innovation, in the securitized market, originated at Smith Breeden, where its founders developed early option-adjusted spread modeling techniques for MBS valuation. The innovative approach continues under Victory Capital, which manages over $10.8 billion for insurance companies. We are focused on delivering competitive risk-adjusted returns, while considering the accounting, regulatory, and capital management needs of our insurance clients to create long-term partnerships.  We understand the unique needs of insurers, and we provide customized and efficient risk-based capital solutions that align with insurers' risk tolerances and investment objectives.

Source: *Pioneer Investments, a Victory Capital Investment Franchise, as of September 30, 2026
 

Jay Alexander, CFA, CAIA
Managing Director, Institutional Markets
jalexander@vcm.com
+1 (612) 965-5426

 
Emma White
Director, Institutional Markets
ewhite@vcm.com
+1 (617) 422-4569

Marko Komarynsky
Director, Institutional Markets
mkomarynsky@vcm.com
+1 (210) 697-3613
 

View the contributor page

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor .

Create an account

Already have an account ? Sign in

Ѐ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ѝ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С ΄ ΅ Ά · Έ Ή Ί Ό Ύ Ώ ΐ Α Β Γ Δ Ε Ζ Η Θ Ι Κ Λ Μ Ν Ξ Ο Π Ρ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С Т У Ф Х Ц Ч Ш Ā ā Ă ă Ą ą Ć ć Ĉ ĉ Ċ ċ Č č Ď ď Đ đ Ē ē Ĕ ĕ Ė fi fl œ æ ß