Pioneer Investments -

Agency Mortgage-Backed Securities (MBS) Market - August

PioneerFeatured

Tyler Patla - Managing Director, Deputy Director of Core Fixed Income, Director of Agency Mortgages, Portfolio Manager


Agency MBS Outperformed in August

The US Treasury yield curve bear-flattened in August after Treasury announced an initiative to lower long-term yields and Fed Chair Warsh was surprisingly hawkish in his speech at the Jackson Hole conference. After the 30-year Treasury bond yield hit 5.3%, its highest level in 19 years, Treasury Secretary Bessent announced a doubling of the size of the Treasury’s debt buyback operations for longer-term securities. Then, Fed Chair Warsh’s speech at Jackson Hole sounded more hawkish than expected, characterizing the economy as strong and resilient and unequivocally committing to the 2% personal consumption expenditures (PCE) inflation target. Markets responded by increasing the implied probability of a rate hike in September from 38% to 65%, and the Treasury yield curve moved higher and flatter.

Although we noted in last month’s issue that agency MBS tends to underperform in bear steepening environments like August’s, the mortgage market ground tighter for most of the month before weakening into its final days. The Bloomberg US MBS Index returned +0.52% on the month, reflecting a +0.23% excess return to Treasuries as sector option-adjusted spread (OAS) tightened by 2bp to +29bp. Interestingly, this occurred after MBS underperformed amidst a steepening yield curve, marking two consecutive months breaking from historical precedent. Outperformance was relatively consistent between lower and higher coupons, and MBS modestly outperformed investment-grade corporate bonds, with the Bloomberg US Corporate Index only outearning Treasuries by 0.12%.

Specified Pool Types Grow with Loan Sizes

For several decades, loans with smaller loan sizes have constituted the most well-established form of convexity protection, which would dampen the impact of faster prepayments and shorter durations when interest rates fall, and the converse when rates rise. Borrowers with smaller loan sizes see smaller benefits to refinance into lower interest rates relative to fixed origination costs, and similarly see less disincentive to move or otherwise repay their loan when market rates have risen.

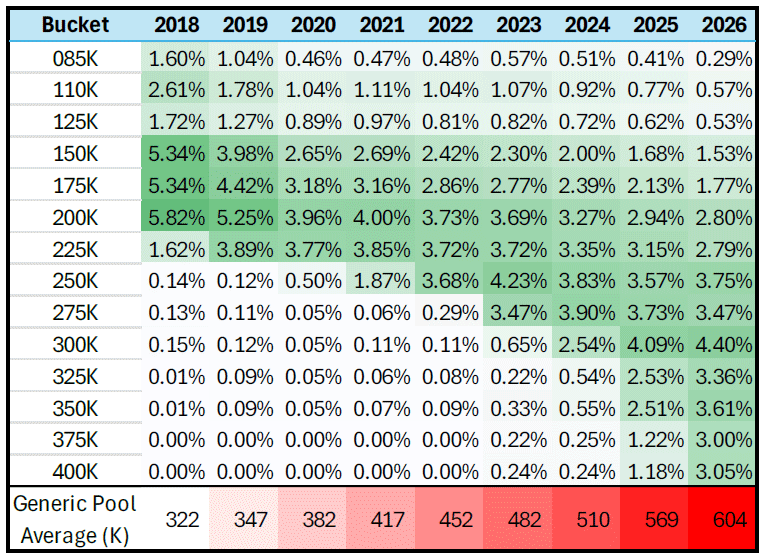
Accelerated growth in home prices since 2020, however, have materially changed the size of average loans, and in turn, how originators choose to pool and how investors choose to purchase MBS. In the following table, we illustrate the percentage of total MBS issuance (in dollar terms) that has been issued in securities with maximum loan sizes in each bucket. While hardly any specified pools were issued with maximum loan sizes above $225,000 pre-COVID-19, that behavior crept higher, until it jumped from $300,000 to $400,000 over the past two years. By extension, since those loans are held out of generic, cheapest-to-deliver (CTD) securities, the average loan size in those multi-issuer securities has climbed even faster than national home prices, almost doubling from 2018 to 2026 and illustrated in the bottom row. What is known in MBS investor circles as a perpetually-deteriorating CTD, this increases the potential advantage of a fixed loan size below the CTD.

As a potentially offsetting impact, digitization and AI-enhancements to the origination process has begun to reduce closing times and costs. This could negate some of the advantages of smaller loan sizes by reducing the price and time associated with refinancing, putting a $300,000 and $600,000 on a more even incentive structure and ensuing reaction function. We will continue to monitor these dynamics as we assess relative value in this space.

Image
Table

Source: Riskspan, Pioneer Investments, as of August 31, 2026
 

Outlook: Technicals Stuck in Neutral, Trade the Range

Consistent with prior months, we still believe agency MBS spreads will remain range-bound, with movement in the range influenced by exogenous headlines, interest rate curve-based correlations, and short-term dynamics. The passthrough from geopolitical headlines and inflation data to MBS spreads with implicit guardrails is a function of balanced valuations, technicals, and fundamentals, with the medium-term outlook for these dynamics shifting.

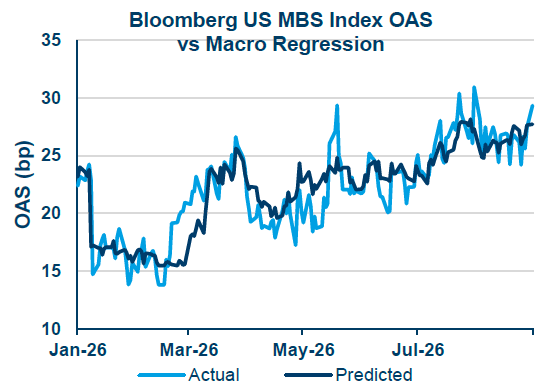
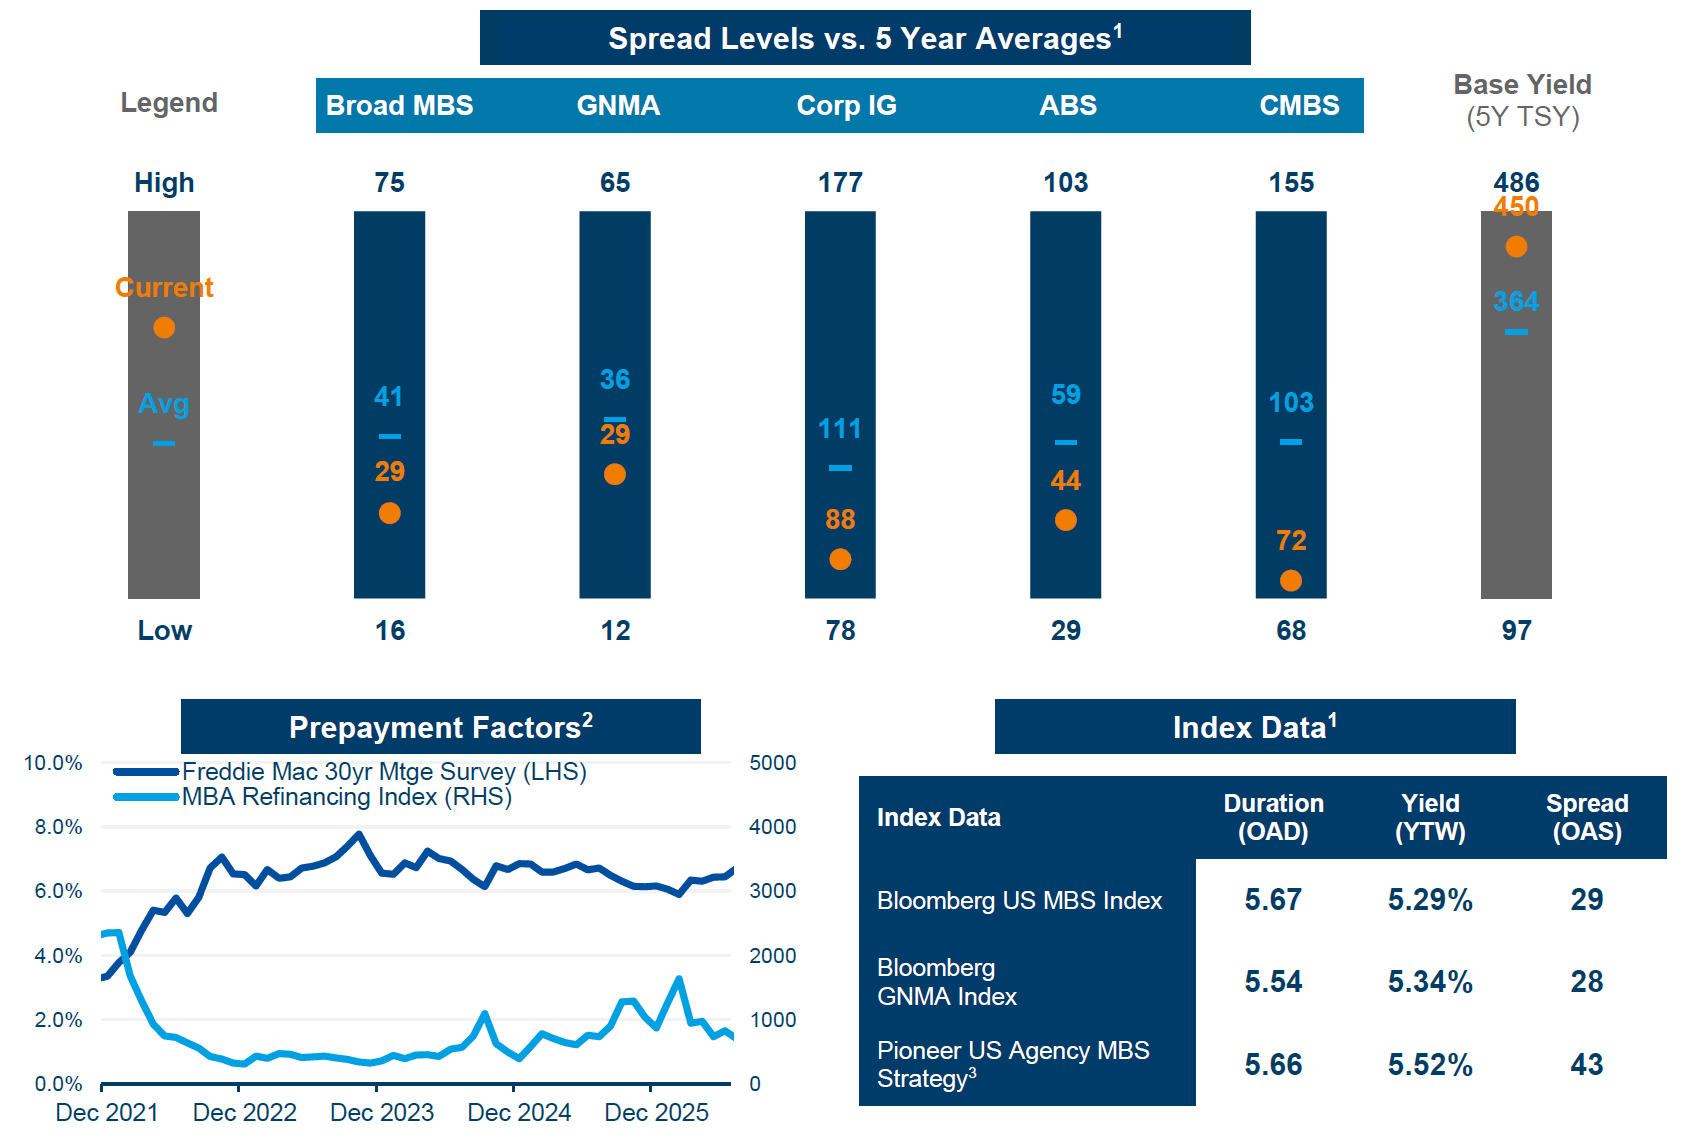
Valuations: Mortgage OAS to Treasuries is slightly tight to its 5-year and 10-year averages, which looks attractive when comparing current spreads on the Bloomberg US Corporate Index relative to its respective spread history. Mortgages have now lagged corporates YTD as some asset managers have reduced their overweight to MBS to participate in record levels of corporate bond issuance, particularly as the weight of MBS in fixed income indices has declined. Meanwhile, thanks to negative swap spreads, OAS to swaps is at 71bp, above its average over the past decade, and many potential marginal buyers of MBS tend to hedge with swaps.
 

Image
Graph showing Bloomberg US MBS Index OAS vs Macro Regression

Source: Bloomberg, Pioneer Investments, as of August 31, 2026
 

Technicals: We continue to wait for the updated Basel III Endgame proposal to inspire banks to make up for a lack of purchases in recent years. However, while current carry relative to intere st on reserve balances (IORB) is at recent highs, a flatter yield curve generates higher forward curves, which project banks’ net interest margin on MBS to decay amid more hawkish Fed expectations. Similarly, while currency-hedged carry for overseas investors is relatively strong, it is not projected to rise more if forward expectations are realized. Fannie Mae and Freddie Mac added MBS aggressively in Q1 as directed by the Trump administration, but have curiously stopped growing their portfolios in the past few months, with no official communication whether we should expect purchases to resume to meet 2026 demand targets. Mortgage real estate investment trusts (mREITs) have traded above book value and are positioned with relatively low leverage, which may facilitate further MBS purchases.

Fundamentals: AI advancements and isolated prepayment data suggest more efficient refinancing the next time mortgage rates fall, with the potential for streamline refinancing in conventional loans that could meaningfully accelerate cheapest-to-deliver prepayments. However, current data continues to support more benign prepayment outlooks, with any spike in recent years short-lived and explainable by loan closing timeline adjustments. Prepayments have slowed significantly over the past few months as media focus on mortgage rates has disappeared, suggesting many borrowers may be less reactive to a potential sustained drop in rates. With the recent selloff, the market sits even further from meaningful prepayment risk. If faster speeds come to pass, such an environment also increases the potential for security selection opportunities, as do potential dislocations from changing government policies.

The balanced considerations above and price-sensitivity of marginal investors have influenced us to trade around in modest size as headlines moved markets. Broadly, the willingness of asset managers to sell at tighter spreads, with banks, overseas investors, mREITs, and agencies willing to buy at wider spreads, can provide both the resistance and support to maintain the range as macro factors oscillate. While net issuance of MBS is quite low, demand from banks, overseas investors, and the agencies could weaken or disappear in 2027, reducing (but not extinguishing) our optimism over a longer timeline. Dedicated MBS portfolios are positioned more closely to the index than the long-term average, but we view agency MBS more favorably as a positive contributor to aggregate, multi-sector, or multi-asset portfolios. We prefer MBS relative to swaps rather than to Treasuries, particularly because current marginal sources of demand hedge this way. Additionally, we are optimistic that prepayment uncertainty and headline-induced dislocations may provide dynamic allocation and security selection opportunities.

READ MORE FROM Pioneer Investments


Securitized Market Dashboard

Image
Spread Levels vs. 5 year average, prepayment factors, index data

Source: Bloomberg, as of August 31, 2026
1 Index Data: Bloomberg US MBS Index, Bloomberg GNMA Index, Bloomberg US Aggregate Corporate Average OAS, Bloomberg US Investment Grade ABS Index, Bloomberg US Investment Grade CMBS Index.
2 S&P/Experian First Mortgage Default Index, MBA Refinance Index.
3 The characteristics are of the representative account (gross, USD) in the US Agency MBS composite. Gross-of-fees returns are presented before management and custodial fees but after any transaction costs.

Image
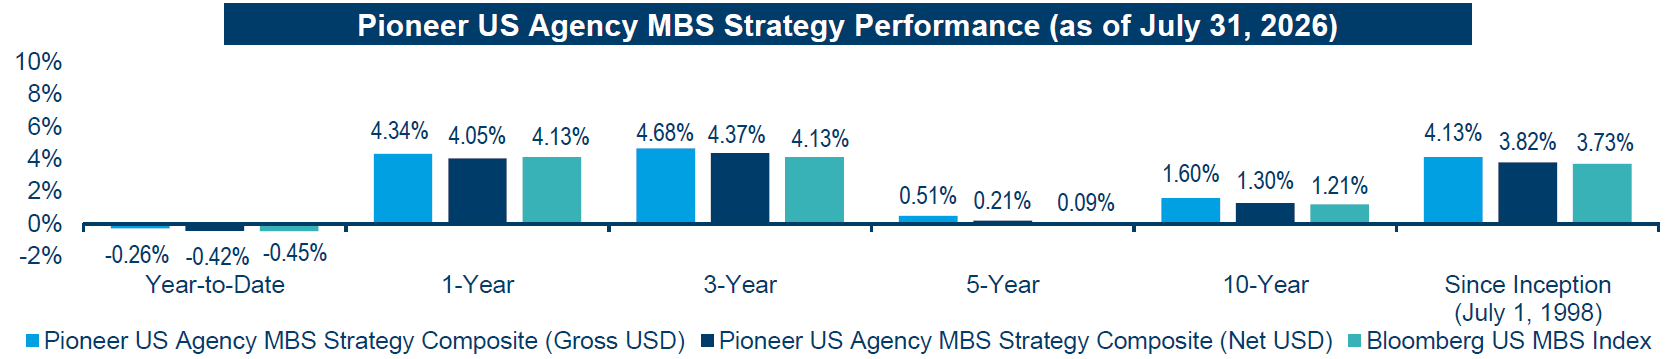
Pioneer US agency mbs strategy performance

Source: Pioneer Investments, as of July 31, 2026
Performance prior to April 1, 2025, occurred while the portfolio management team was affiliated with a prior firm. Such members of the portfolio management team were responsible for investment decisions at the prior firm and the decision-making process has remained intact.
Returns greater than one year are annualized. Returns are expressed in US dollars and reflect the reinvestment of dividends and other earnings.
Gross-of-fees returns are presented before management and custodial fees but after any transaction costs. The composite net-of-fees returns reflect net of model fees and are calculated in the same manner as gross of fee returns using the Time Weighted Rate of Return method. Actual fees may vary depending on, among other things, the applicable fee schedule and portfolio size.
Please refer to the GIPS® Report for additional information.
Past performance is no guarantee of future results.
All investing involves risk, including the possible loss of principal. An investment should be made with an understanding of the risks involved with owning a particular security or asset class.
Unless otherwise stated, all information contained in this document is from Pioneer Investments, a Victory Capital® Investment Franchise. The views expressed in this presentation are those of Pioneer Investments as of the date noted, and are subject to change at any time. These views should not be relied upon as investment advice, as securities recommendations, or as an indication of trading intent on behalf of any of portfolio.
The services and any securities described in this document may not be registered for sale with the relevant authority in your jurisdiction and may not be regulated or supervised by any governmental or similar authority in your jurisdiction. Where unregistered, they may not be sold or offered except in the circumstances permitted by law. Pioneer Investments is not making any representation nor does this document constitute a representation with respect to (i) the eligibility of any recipients of this document to acquire any securities or any services described herein in any jurisdiction or (ii) the eligibility of any recipients of this document to receive this document in any jurisdiction. If you are in doubt about the content of this document or your eligibility, you should obtain independent professional advice.
Sector allocations are subject to change. Holdings are subject to change and should not be construed as investment advice or a recommendation to buy, sell, or hold any security. Information relating to portfolio holdings is based on the representative account in the composite and may vary for other accounts in the strategy due to asset size, client guidelines and other factors.
Indexes are unmanaged; their returns include reinvestment of dividends and other income but do not reflect management fees, transaction costs or expenses. It is not possible to invest directly in an index. Past performance does not guarantee future results.
Advisory Services offered by Victory Capital Management Inc.
©2026 Victory Capital Management Inc.

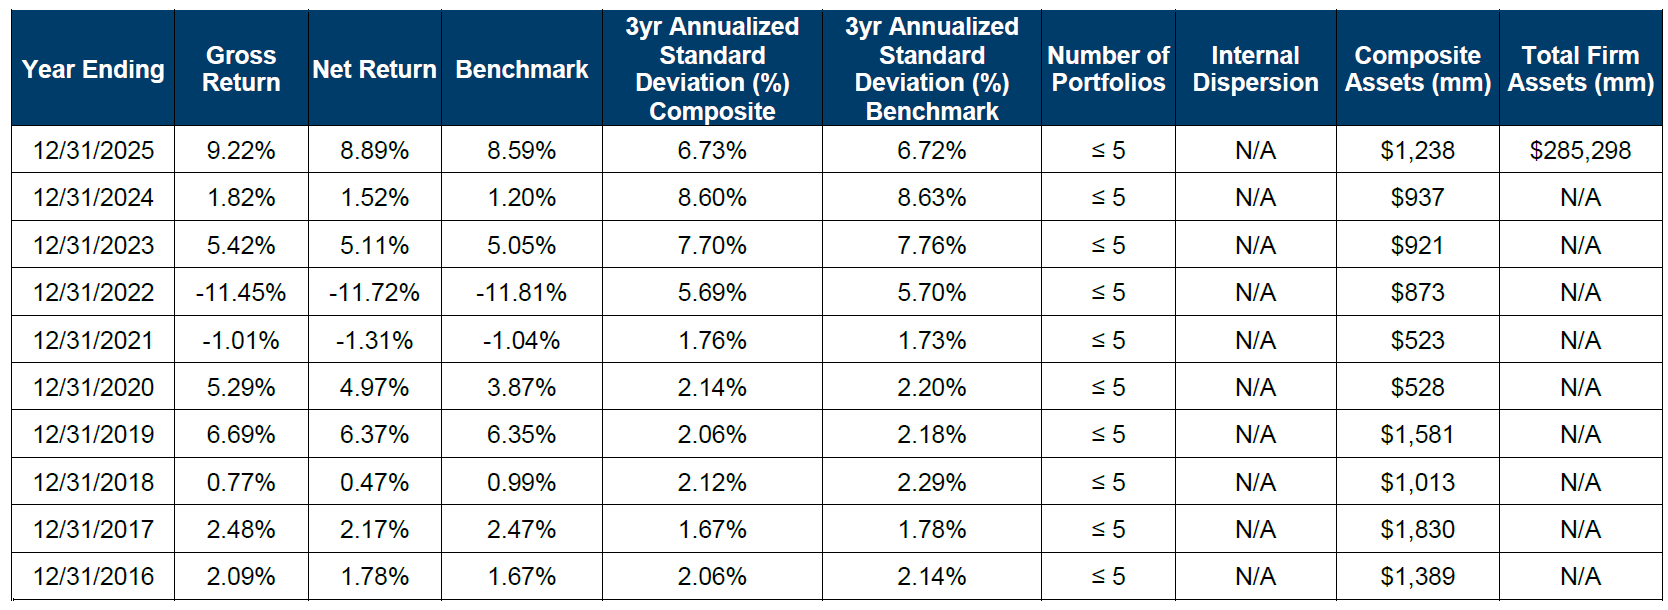
Pioneer US Agency MBS Strategy Composite Performance

Image
Table

Firm assets prior to 2018 are shown as "N/A" above as the composite was not part of the firm.

1. Victory Capital Management Inc. claims compliance with the Global Investment Performance Standards (GIPS®) and has prepared and presented this report in compliance with the GIPS standards. Victory Capital Management Inc. has been independently verified for the periods January 1,2001 through December 31, 2025. The verification report is available upon request. A firm that claims compliance with the GIPS standards must establish policies and procedures for complying with all the applicable requirements of the GIPS standards. Verification provides assurance on whether the firm's policies and procedures related to composite and pooled fund maintenance, as well as the calculation, presentation, and distribution of performance, have been designed in compliance with the GIPS standards and have been implemented on a firm-wide basis. Verification does not provide assurance on the accuracy of any specific performance report.

2. Victory Capital Management Inc. (VCM) is a diversified global investment adviser registered under the Investment Advisers Act of 1940 and comprises multiple investment franchises: Integrity Asset Management, New Energy Capital Partners, Pioneer Investments, RS Investments, Sycamore Capital, Trivalent Investments, Victory Income Investors, and the Victory Capital Solutions Platform. RS Investments and Sophus Capital became a part of the VCM GIPS firm effective January 1, 2017; Victory Income Investors, effective July 1, 2019; THB Asset Management, effective March 1, 2021; New Energy Capital effective November 1, 2021; and Amundi Asset Management US, Inc. (renamed to “Pioneer Investments”), effective April 1, 2025. Effective July 1, 2025, Newbridge Asset Management, Sophus Capital and THB Asset Management are no longer part of the GIPS firm. Effective December 1, 2025, Munder Capital Management is no longer part of the GIPS firm.

3. The Pioneer US Agency MBS Strategy seeks to produce returns in excess of the index by actively managing a portfolio consisting primarily of agency mortgage-backed securities. The composite creation date is June 1998, and the composite inception date is July 1, 1998. The benchmark of the composite is the Bloomberg US MBS Index.


20260911-5919228

Share this post

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor

Register

Contacts


Image
Pioneer Stacked Logo FL


Pioneer Investments manages $147 billion in assets and has a long-standing history of innovation with deep expertise managing fixed income portfolios and creating customized solutions within the more opportunistic areas of the securitized market.

Pioneer Investments’ culture of innovation, in the securitized market, originated at Smith Breeden, where its founders developed early option-adjusted spread modeling techniques for MBS valuation. The innovative approach continues under Victory Capital, which manages over $10.7 billion for insurance companies. We are focused on delivering competitive risk-adjusted returns, while considering the accounting, regulatory, and capital management needs of our insurance clients to create long-term partnerships.  We understand the unique needs of insurers, and we provide customized and efficient risk-based capital solutions that align with insurers' risk tolerances and investment objectives.

Source: *Pioneer Investments, a Victory Capital Investment Franchise, as of June 30, 2026
 

Jay Alexander, CFA, CAIA
Managing Director, Institutional Markets
jalexander@vcm.com
+1 (612) 965-5426

 
Emma White
Director, Institutional Markets
ewhite@vcm.com
+1 (617) 422-4569

Marko Komarynsky
Director, Institutional Markets
mkomarynsky@vcm.com
+1 (210) 697-3613
 

View the contributor page

Sign Up Now for Full Access to Articles and Podcasts!

Unlock full access to our vast content library by registering as an institutional investor .

Create an account

Already have an account ? Sign in

Ѐ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ѝ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С ΄ ΅ Ά · Έ Ή Ί Ό Ύ Ώ ΐ Α Β Γ Δ Ε Ζ Η Θ Ι Κ Λ Μ Ν Ξ Ο Π Ρ Ё Ђ Ѓ Є Ѕ І Ї Ј Љ Њ Ћ Ќ Ў Џ А Б В Г Д Е Ж З И Й К Л М Н О П Р С Т У Ф Х Ц Ч Ш Ā ā Ă ă Ą ą Ć ć Ĉ ĉ Ċ ċ Č č Ď ď Đ đ Ē ē Ĕ ĕ Ė fi fl œ æ ß